The report explores the critical factors shaping Luxembourg’s residential real estate market in 2026 across the following topics:
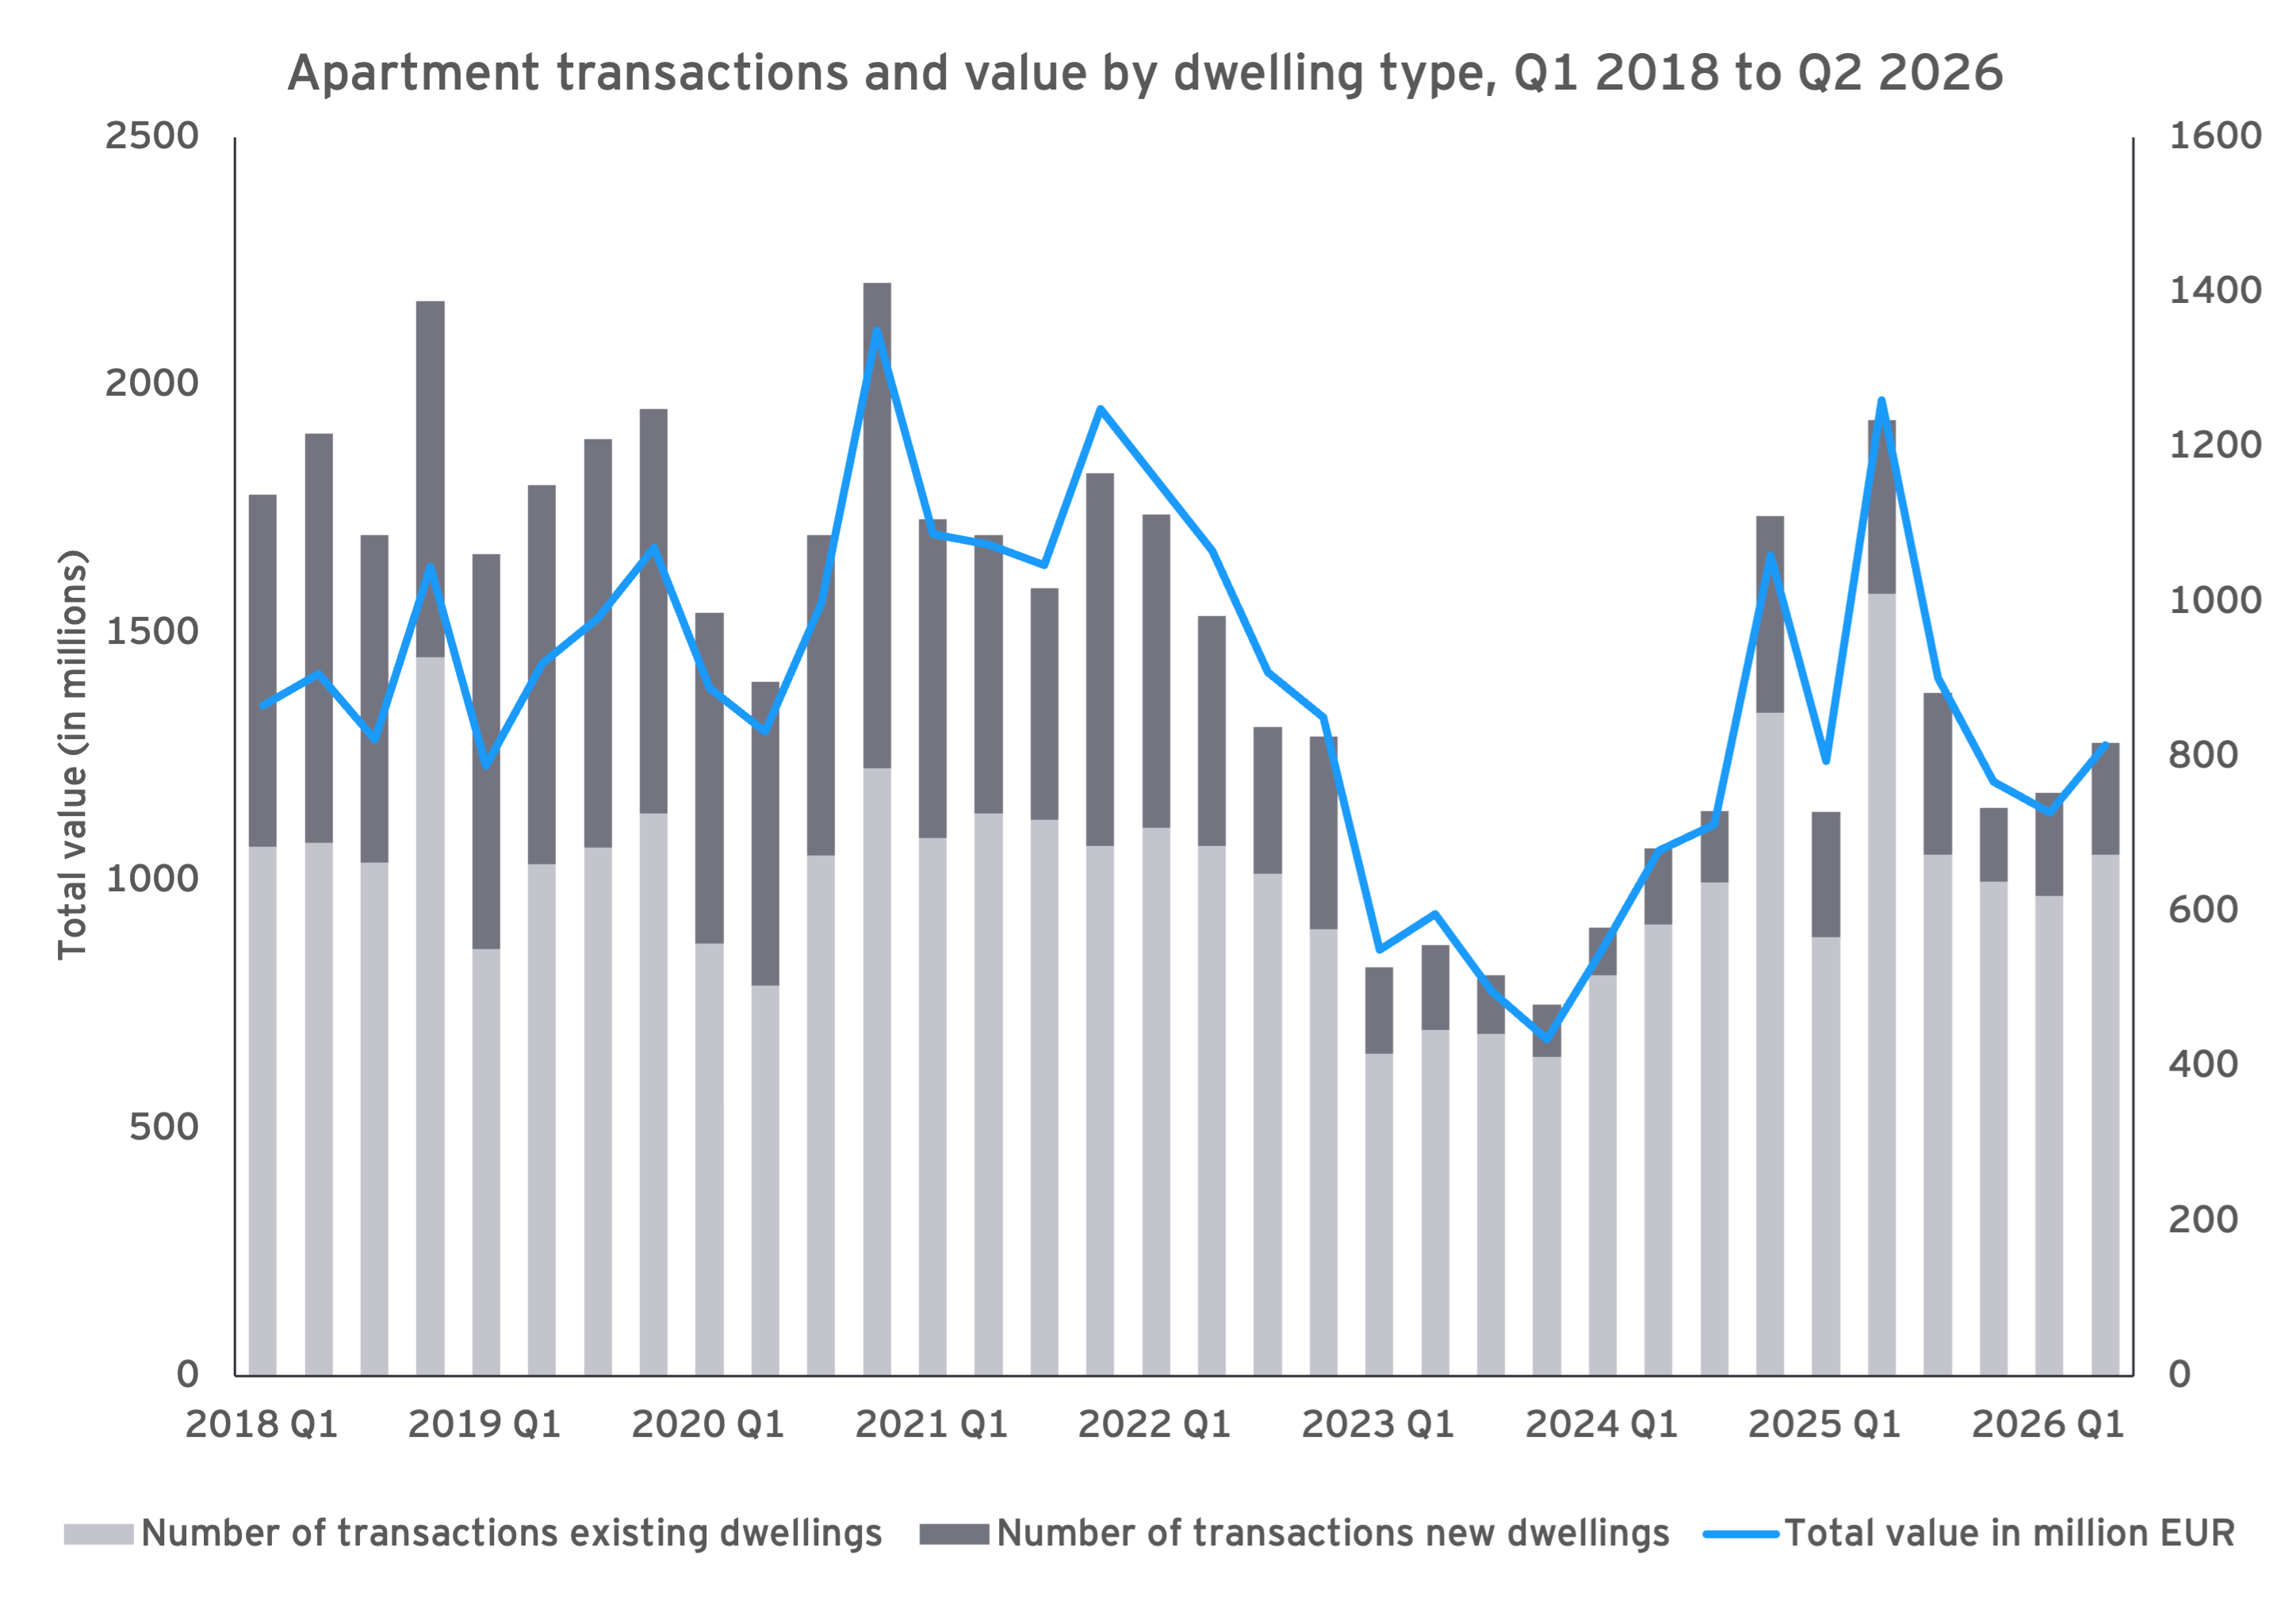
Transaction volumes remain above 2024 levels despite a slowdown. Following a strong recovery in 2024 and 2025, apartment, house and building-land transactions declined in H1 2026 but remain well above the levels recorded in H1 2024.
Prices remain below their 2022 peak. Existing apartment prices declined 2.2% year on year in Q2 2026 and remain approximately 11% below the market peak reached in mid-2022.
The market recovery has lost momentum. Transaction activity weakened across apartments, houses and building land during the first half of 2026, partly reflecting exceptionally strong comparative figures from 2025.
The new-build segment remains the market's principal weakness. VEFA transactions fell by more than 28% year on year, while average VEFA prices and market share both continued to decline.
Supply constraints continue to underpin the market. Population growth of 1.3%, lower building permit issuance and rising construction costs continue to reinforce Luxembourg's structural housing shortage.
Interest rates have turned upwards again. The ECB resumed monetary tightening in September 2026, increasing pressure on borrowers and contributing to higher fixed mortgage rates.
Rental market dynamics remain strong. Advertised rents continued to rise, supported by demand for smaller units and continued pressure on the rental housing market.