
EY refers to the global organization, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients.
Recent Searches
Press release
08 Sep 2026
|
Jakarta, Indonesia
Southeast Asia’s Financial Services M&A Deal Volume Remained Stable in H1 2026 Despite Lower Deal Value as Indonesia Sees Strategic Deal Activity
- Total of 31 disclosed financial services sector deals valued at US$936m across Southeast Asia in H1 2026; globally, there were 1,137 announced deals worth over US$134.5b in value
- Indonesia's financial services M&A landscape remains underpinned by regulatory-led consolidation and strong investor appetite for an under-penetrated market.
- Deal activity in Indonesia is increasingly driven by strategic expansion, with buyers seeking distribution, adjacent financial-services capabilities and greater customer reach, alongside growing interest in wealth and asset management.
JAKARTA, 8 September 2026. Following a decade-high peak last year, the number of announced or completed M&A transactions in the global financial services sector continued to rise further in the first half of this year, with a 3% year-on-year increase in reported deals over the same time period, according to the latest EY financial services M&A analysis.
Banks, insurers and asset managers across the world’s major financial services markets publicly disclosed 1,137 deals in H1 2026, compared with 1,101 deals in H1 2025. However, total disclosed value for global financial services deals declined – from US$191.3b in H1 2025 to US$134.5b in H1 2026 – with 25 megadeals announced above US$1b in value, representing 80% of total deal value. This compares to 37 deals above US$1b in H1 2025 and 55 deals in H2 2025.
Over H1 2026, the 10 biggest deals globally accounted for 58% of total value (US$78.7b). Expanding this view to the top 20, these deals accounted for 75% of total value (US$100.5b). This is largely consistent with H1 2025, where the 10 biggest deals accounted for 58% of total value (US$111.3b), and the 20 biggest deals accounted for 72% of total value (US$138.3b).
Omar Ali, EY Global Financial Services Leader, comments:
“Financial services firms have now adapted to operating in heightened uncertainty as standard, incorporating volatility into business-as-usual. But unpredictability has an impact, and is intensified by slower global economic growth, rising inflation and ongoing supply shocks. As such, despite the number of transactions rising, deal value in H1 this year across the world’s major markets is down on 2025 levels, as significantly fewer transactions completed over the US$1b mark.
However, despite market challenges, confidence is stabilizing and boards are eager to accelerate the delivery of their strategic plans. As we look to the second half of 2026, we expect a pickup in dealmaking, as banks, insurers and asset managers increasingly look to M&A to achieve competitive growth and transformation.”
Indonesia financial services M&A continues to evolve in H1 2026
In Indonesia, financial services M&A activity continues to be underpinned by regulatory-led consolidation, particularly through the Financial Services Authority's (OJK) efforts to strengthen capital levels across smaller banks and multifinance companies. Strong investor appetite for Indonesia's under-penetrated financial-services market also continues to support deals activity. Recent landmark transactions, such as OCBC's acquisition of HSBC's wealth and premier banking portfolio in Indonesia, as well as BTN's acquisition of SMBC Indonesia's pension loan portfolio, illustrate this continued interest.
Reuben Tirtawidjaja, EY-Parthenon Indonesia Strategy and Transactions Partner, states:
“Increasingly, strategic buyers are pursuing distribution, licences into adjacent financial services businesses, and greater customer reach, rather than pure balance-sheet scale.”
Growing interest is also emerging in wealth and asset management in H1 2026, as investors seek to tap into Indonesia's expanding affluent segment and rising demand for wealth products. This marks a pivot toward fee-based, capital-light business models with structural growth potential, mirroring wider global trends across the financial-services sector. Looking ahead to the remainder of 2026, further opportunities are expected to emerge from ongoing consolidation and from established players expanding into new customer segments.
Reuben adds:
“Valuation gaps between buyers and sellers remain a challenge, particularly as investors increasingly price in geopolitical and macroeconomic headwinds such as currency volatility and the country's credit-rating pressures. Even so, we anticipate sustained interest across wealth and asset management, insurance, including insurtech, where higher minimum-equity requirements are driving consolidation, multifinance, and digital payments and lending platforms, complemented by continued consolidation among smaller banks in response to regulatory scale requirements.”
H1 2026 financial services M&A overview
Asia and Oceania
Across Asian and Oceanian markets, M&A activity declined in H1 2026, with a 14% half year-on-year decrease in the number of publicly disclosed deals, totaling 147 deals compared to 170 in H1 2025. The total disclosed deal value decreased modestly, falling from US$17.8b in H1 2025 to US$15.8b in H1 2026.
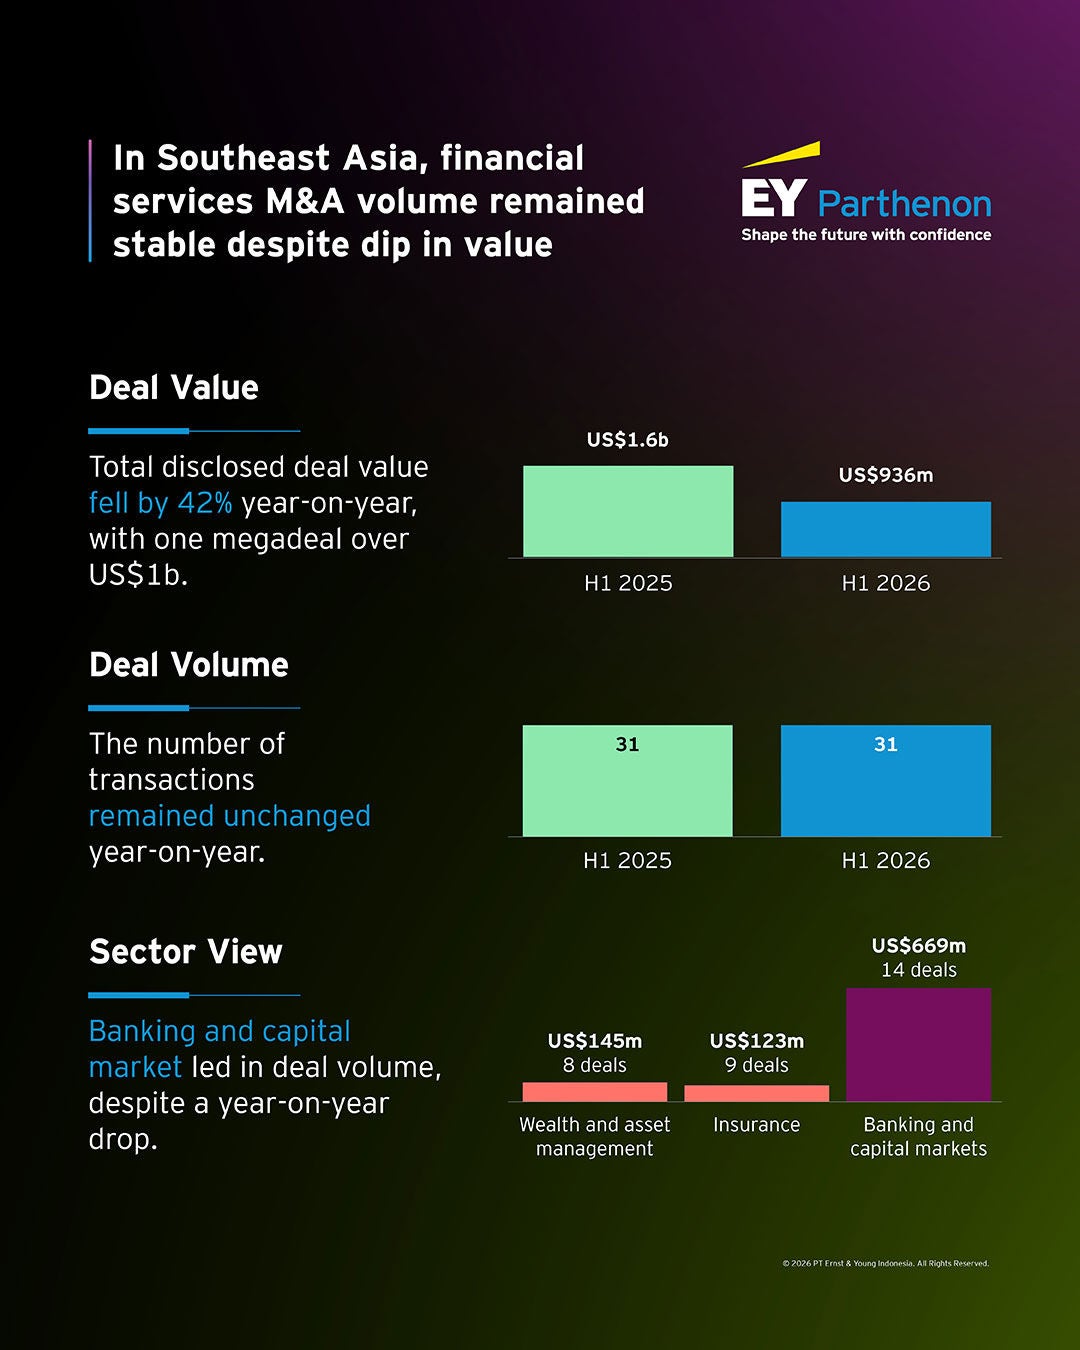
Southeast Asia Financial Services M&A Activity H1 2026 - Overview
In Southeast Asia (SEA), M&A activity remained stable in H1 2026, with the number of publicly disclosed deals unchanged at 31 year-on-year. Total disclosed deal value fell from US$1.6b in H1 2025 to US$936m in H1 2026.
Stuart Last, EY-Parthenon Partner, Financial Services, Ernst & Young Solutions LLP, comments:
“The stability in deal activity across Southeast Asia's financial services sector reflected a market that remains engaged despite economic and geopolitical volatility. While disclosed deal value moderated in H1 2026, M&A activity continued to concentrate in smaller- and mid-sized transactions. This suggests that investors are pursuing opportunities with a clear, strategic rationale, pointing to a continued disciplined approach to dealmaking. That said, we anticipate a pickup in larger transactions in the second half of 2026 as financing conditions improve and more scaled assets come to market.”
Europe
Across Europe, M&A activity rose in H1 2026, with a 7% half year-on-year increase in the number of publicly disclosed deals, reaching 375 deals compared to 350 in H1 2025. The total disclosed deal value however, fell, declining from US$74.9b in H1 2025 to US$63.9b in H1 2026.
North America
In the United States and Canada, M&A activity rose in H1 2026, with an 8% half year-on-year increase in the number of publicly disclosed deals, totaling 546 deals compared to 504 deals in H1 2025. The total disclosed deal value however declined materially, from US$91.8b in H1 2025 to US$48.5b in H1 2026, primarily due to a drop in large-cap deals, which fell from 19 in H1 2025 to 8 in H1 2026.
Sector specific M&A activity
Asia and Oceania
- Banking and capital markets deal volume decreased from 87 in H1 2025 to 77 in H1 2026, and deal value increased from US$6.4b in H1 2025 to US$11.3b in H1 2026.
- Insurance deal volume fell from 41 in H1 2025 to 31 in H1 2026, and deal value also declined from US$5.0b in H1 2025 to US$2.1b in H1 2026.
- Wealth and asset management deal volume decreased from 42 in H1 2025 to 39 in H1 2026, while deal value significantly declined from US$6.5b in H1 2025 to US$2.4b in H1 2026.
The number of non-Asian and Oceanian firms acquiring Asian and Oceanian targets increased from 23 in H1 2025 to 28 in H1 2026, and the total disclosed deal value also increased from US$1.6b in H1 2025 to US$1.9b in H1 2026. The number of Asian and Oceanian firms acquiring targets from other markets remained flat at 14 in both H1 2025 and H1 2026, while total disclosed deal value decreased significantly from US$11.8b in H1 2025 to US$1.1b in H1 2026.
Within SEA,
- Banking and capital market deal volume declined from 20 in H1 2025 to 14 in H1 2026, while deal value dropped from US$1.1b in H1 2025 to US$669m in H1 2026.
- Insurance deal volume increased from eight in H1 2025 to nine in H1 2026, while deal value fell from US$478m in H1 2025 to US$123m in H1 2026.
- Wealth and asset management deal volume rose from three in H1 2025 to eight in H1 2026, while deal value increased significantly from US$0.8m in H1 2025 to US$145m in H1 2026.
The number of non-SEA firms acquiring SEA targets decreased from seven in H1 2025 to five in H1 2026. Conversely, total publicly disclosed deal value increased from US$344m in H1 2025 to US$410m in H1 2026.
Last adds:
“The sub-sector trends in H1 2026 reflect shifting areas of investor focus within Southeast Asia's financial services landscape. While deal activity in banking dropped, the insurance and wealth and asset management sub sectors recorded growth in deal volumes. The sharp increase in wealth and asset management deal value points to growing investor interest in platforms and capabilities that can capitalize on the region’s expanding affluent population and rising demand for wealth solutions.
At the same time, the increase in disclosed deal value from non-Southeast Asian acquirers suggests that international investors continue to see attractive opportunities in Southeast Asia, despite current macroeconomic conditions.”
Europe
- Banking and capital markets deals decreased from 96 in H1 2025 to 88 in H1 2026, with deal value falling significantly from US$50.7b in H1 2025 to US$19.3b in H1 2026.
- Insurance deals increased from 146 in H1 2025 to 153 in H1 2026, while deal value declined from US$21.6b in H1 2025 to US$13.4b in H1 2026.
- Wealth and asset management deals rose from 108 deals in H1 2025 to 134 in H1 2026, with deal value rising markedly from US$2.6b in H1 2025 to US$31.1b in H1 2026. This uplift was largely driven by one deal valued at US$13.4b.
The number of non-European firms acquiring European targets increased from 56 in H1 2025 to 67 in H1 2026, while total disclosed deal value increased significantly, rising from US$15.2b in H1 2025 to US$24.3b in H1 2026. The number of European firms acquiring targets from other markets remained flat at 31 in both H1 2025 and H1 2026, while total disclosed deal value increased materially from US$0.5b in H1 2025 to US$16.3b in H1 2026.
North America
- Banking and capital markets deals rose from 123 in H1 2025 to 146 in H1 2026, while deal value declined significantly, from US$62.6b in H1 2025 to US$30.1b in H1 2026.
- Insurance deals fell from 204 in H1 2025 to 187 in H1 2026, and deal value also fell, from US$20.9b in H1 2025 to US$12.3b in H1 2026.
- Wealth and asset management deals rose from 177 in H1 2025 to 213 in H1 2026, while deal value declined from US$8.3b in H1 2025 to US$6.0b in H1 2026.
The number of non-US or Canadian firms acquiring US and Canadian targets increased from 23 in H1 2025 to 30 in H1 2026, and the total disclosed deal value rose significantly from US$4.8b in H1 2025 to US$15.9b in H1 2026. The number of US and Canadian firms acquiring targets from other markets remained flat at 70 in both H1 2025 and H1 2026, while total disclosed deal value increased from US$12.8b in H1 2025 to US$19.8b in H1 2026.
-ends-
Notes to editors:
- Deals include transactions (announced or completed) where the target is in one of the three financial services sectors: banking and capital markets, insurance, or wealth and asset management
- Deal values are attributed to the date of deal announcement
- European markets cover the entire region without exception
- North American markets cover the US and Canada
- Asian and Oceanian markets include: India, Pakistan, Japan, Singapore, Hong Kong, Chinese mainland, Australia, Indonesia, New Zealand, Sri Lanka, South Korea, Thailand, Philippines, Vietnam, Malaysia, Bangladesh, Taiwan, Cambodia, Nepal, Macau, Papua N Guinea, North Korea, Fiji, Maldives, Western Samoa, Brunei, Mongolia, Myanmar, Laos, Guam, Solomon Islands, Vanuatu
- Equity investments were included
- PE/VC targets, IPOs and joint ventures were not included
- Deals where less than 20% (disclosed) of the company or a minority stake was acquired have been excluded
- Data range: 1 January 2026 – 30 June 2026
- There is no minimum disclosed value deal threshold
About EY
EY is building a better working world by creating new value for clients, people, society and the planet, while building trust in capital markets.
Enabled by data, AI and advanced technology, EY teams help clients shape the future with confidence and develop answers for the most pressing issues of today and tomorrow.
EY teams work across a full spectrum of services in assurance, consulting, tax, strategy and transactions. Fueled by sector insights, a globally connected, multidisciplinary network and diverse ecosystem partners, EY teams can provide services in more than 150 countries and territories.
All in to shape the future with confidence.
EY refers to the global organization, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients. Information about how EY collects and uses personal data and a description of the rights individuals have under data protection legislation are available via ey.com/privacy. EY member firms do not practice law where prohibited by local laws. For more information about our organization, please visit ey.com.
This news release has been issued by Ernst & Young Solutions LLP, a member of the global EY organization.