
EY refers to the global organisation, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients.
Recent Searches
In brief:
- Gross Domestic Product (GDP) came in modestly above market and Reserve Bank expectations due to private sector spending.
- While growth was around its historical trend, limited spare capacity and energy and geopolitical shocks are continuing to generate upward inflationary pressure.
- Investment in productivity-enhancing and energy-efficient equipment provides grounds for an improved economic outlook eventually.
From EY Regional Chief Economist Cherelle Murphy
The June-quarter National Accounts show Australia spent heavily on imported technology, electric and hybrid vehicles and energy as it responded to the Middle East conflict and the race to facilitate artificial intelligence.
GDP rose by 0.4 per cent in the quarter and 2.1 per cent over the year, slightly ahead of expectations, but the composition of growth was less encouraging than the headline suggests. Private household consumption growth grew 0.4 per cent, while households saved marginally more of their income. Business investment fell slightly after an elevated level in the March quarter. Dwelling construction was solid. But much of the additional private sector spending leaked into imports, with cars and aircraft and equipment coming from offshore sources. Disappointingly, productivity went backwards over the year.
Households continue to behave cautiously. Consumption growth was concentrated heavily in vehicle purchases, while discretionary spending elsewhere remained subdued. The household saving ratio increased slightly, indicating many consumers remain reluctant to draw down savings despite relatively strong employment conditions.
Business investment presents a similarly mixed picture. Construction of data centres and renewable infrastructure remains exceptionally strong, but investment outside these sectors appears more restrained. Much of the investment associated with digital infrastructure relies on imported equipment, limiting the immediate domestic economic dividend.
Public demand contributed marginally to GDP growth, but the public sector contribution was notably less influential than through much of 2024 and 2025, which is a welcome change in a capacity-constrained economy.
Disappointingly, productivity went backwards over the year, a sign that while Australia is growing, it is not materially improving living standards. Also, price pressures persisted, with a 3.6 per cent annual rise in unit labour costs a reflection of the still-tight labour market.
Exports contributed one of the brighter stories in the National Accounts, rising 0.8 per cent in the quarter, led by coal. Production rebounded after weather disruptions earlier in the year, while strong Asian demand and global energy market uncertainty supported export volumes. Some of the net trade improvement was offset by the large rise in fuel and fertiliser and transport equipment imports.
Although Australia’s coal and mineral export prices increased, the rise was insufficient to offset rising import costs, mainly due to higher fuel prices. Consequently, real national income growth remained relatively subdued.
Australia’s economy is caught between resilient demand and weak supply-side performance. These National Accounts will do little to ease the Reserve Bank’s concerns about the inflation outlook, and we continue to expect that another rate rise will soon be delivered.
Beyond the immediate numbers, there are grounds for cautious optimism. Households facing high interest rates and costs are investing in ways to reduce future expenses, most visibly through electric and hybrid vehicle purchases. Businesses’ high level of investment in digital infrastructure, renewable energy and data centres means that over time, this spending should lift the economy’s productive capacity.
Investment alone will not deliver productivity growth, however. Businesses must combine new technology with stronger skills, better management, redesigned workflows, greater competition and reliable energy infrastructure. We recently conducted modelling which showed AI could lift multifactor productivity by 2.0 to 2.4 per cent over the next decade by improving how efficiently the economy combines labour and capital. (The economic upside of AI for Australia)
Australia is growing, but not yet in the way it needs to. The challenge is to convert investment in artificial intelligence, digital capability and energy-efficient equipment into stronger, sustainable growth that doesn’t add to inflation.
For policymakers, the figures strengthen the case for accelerating the productivity agenda. Regulatory reform, faster project approvals, tax reform, workforce participation initiatives and measures to encourage private investment should remain at the centre of economic policy.
Explore the National Accounts June 2026 in Ten Charts
EV purchases rise amid higher fuel costs
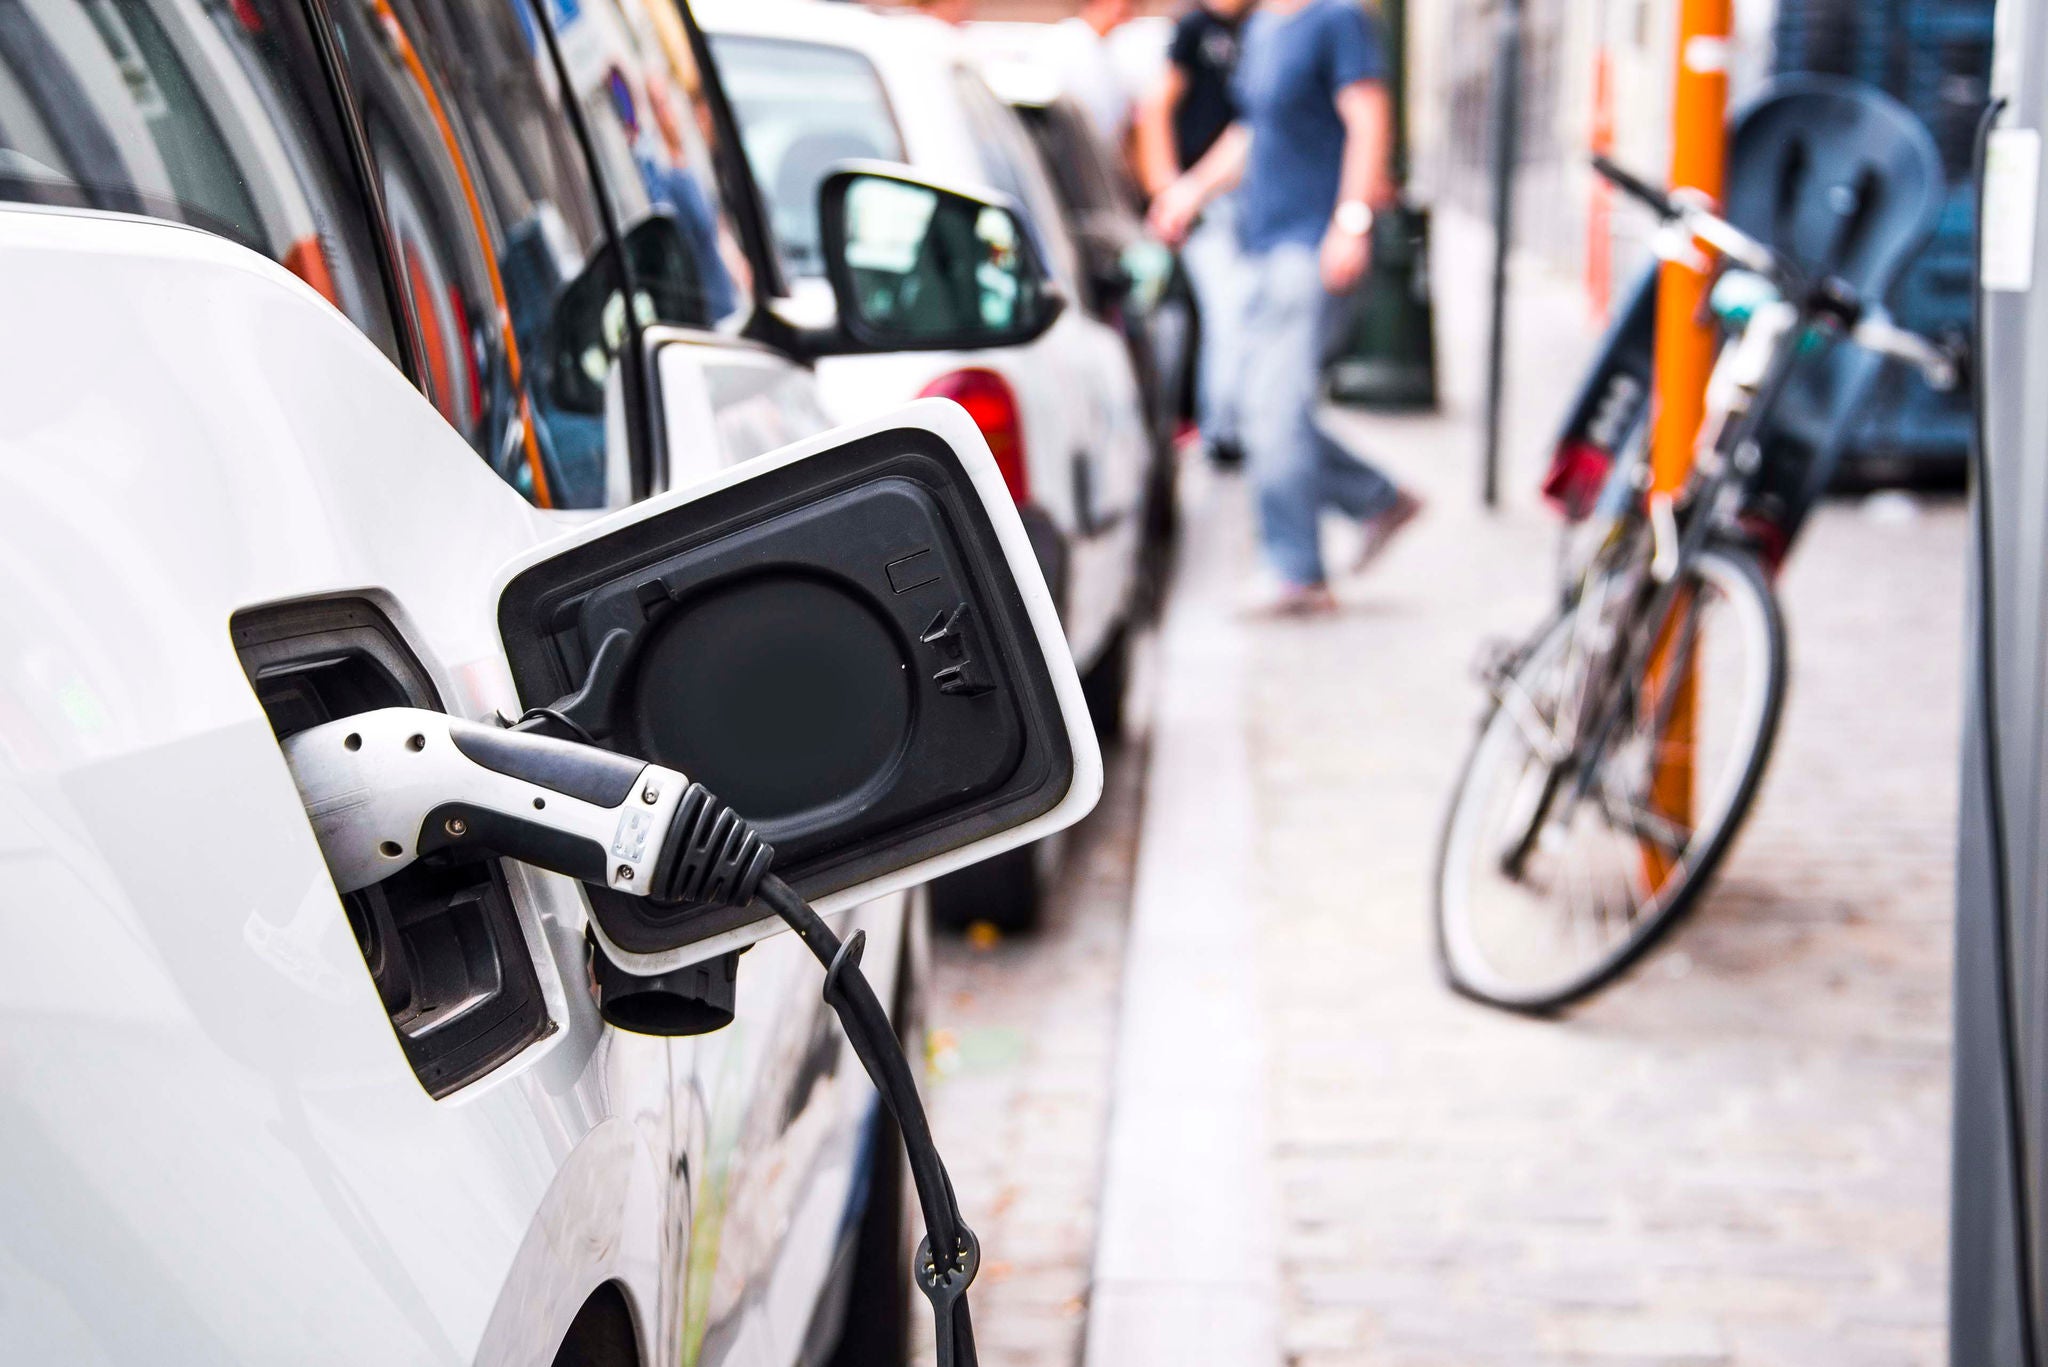
Household consumption increased by 0.4 per cent in the June quarter, contributing 0.2 percentage points to GDP growth. Discretionary spending was the main driver, up 1.4 per cent, reflecting a shift in consumer behaviour as households increased their purchases of electric and hybrid cars to manage higher fuel costs. Outside of car purchases, discretionary spending was subdued, consistent with cost-of-living pressures. Essential spending fell 0.3 per cent as warmer winter conditions led to less demand for electricity and gas.
The tax burden on households remains elevated, with income tax payable less social assistance benefits accounting for 11.7 per cent of disposable income, while the proportion going to interest on dwellings (7.4 per cent) continues to rise after three cash-rate hikes this year. The household saving ratio ticked up slightly to 6.5 per cent, as growth in disposable income outpaced spending.
Annual growth in household consumption was 1.8 per cent in the year to June, moderating from 2.4 per cent in March. This was in line with the Reserve Bank’s forecast, but as real incomes fall, spending momentum is likely to remain gradual as households navigate elevated costs, higher interest rates and ongoing economic uncertainty.
Dwelling investment continued to rise and is now above the long-run average
Dwelling investment growth was strong at 1.6 per cent in the June quarter, after a 1.5 per cent rise in the March quarter. Over the year, dwelling investment growth rose to 5.8 per cent, from 4.2 per cent in the March quarter.
New house building rose 1.7 per cent in the quarter, as builders worked through the ongoing pipeline of projects, and was 6.3 per cent higher over the year. Growth in alterations and additions rose by 1.4 per cent in the June quarter, from 3.7 per cent in the March quarter, and remained elevated in annual terms at 5.1 per cent. Ownership transfer costs fell by 1.9 per cent in the quarter as property market activity decreased. This reflects the impact of recent interest rate increases, the sluggish economy and changes to investor taxation in the Federal Budget in May. In annual terms, ownership transfer costs moderated sharply to 2.2 per cent, from 6.5 per cent in the March quarter.
Dwelling investment as a share of nominal GDP continues to rise, reaching 5.6 per cent from 5.5 per cent in the March quarter, the highest since the December quarter 2018. This partly reflects elevated construction price pressures, which increased further in the June quarter due to higher labour and materials costs. Dwelling approvals rose by 11.7 per cent over the year to July, in trend terms, which points to continued growth in dwelling investment. However, the combined impact of higher construction costs, higher interest rates and lower property prices is expected to weigh on housing construction in future.
Weak productivity and accelerating labour costs remain a concern
Labour productivity – measured by GDP per hour worked – was flat in the quarter, an improvement from the 0.6 per cent fall recorded in the March quarter. Productivity growth decreased by 0.2 per cent in annual terms, which was well below its 20-year pre-pandemic average of 1.2 per cent.
Compensation of employees (COE) – a measure of the economy-wide wages bill – rose by 1.5 per cent during the quarter. The public sector recorded growth of 1.8 per cent supported by health-sector wage increases and new public sector enterprise agreements across a number of states and territories. Private sector COE increased by 1.4 per cent due to rises in the professional services, financial and insurance services, and the construction sectors. In annual terms, COE rose by 6.0 per cent in the June quarter, which was higher than the 5.9 per cent in the previous quarter. This measure contrasts with the more modest Wage Price Index measure (3.2 per cent over the year to June), because it also reflects growth in the number of employees and hours worked.
Nominal unit labour costs – a broader measure of labour costs – accelerated to 1.2 per cent in the quarter. In annual terms, nominal unit labour cost growth increased to 3.6 per cent, from 3.2 per cent in the March quarter. Continued improvements in labour productivity are needed to moderate growth in unit labour costs and reduce inflationary pressures. In the August 2026 Statement on Monetary Policy, the Reserve Bank continued to forecast weak productivity growth in the medium term, signifying the ongoing challenge for future economic prosperity.
Company profits rose 2.4 per cent in the June quarter, led by mining due to increased sales and higher prices for coal, crude oil and lithium. In annual terms, company profits increased by 6.1 per cent.
Escalating input costs keep upward pressure on inflation
Australia's terms of trade fell by 1.6 per cent in the June quarter. Despite a 1.9 per cent increase in export prices, the terms of trade deteriorated as import prices rose more strongly, increasing by 3.5 per cent due to higher fuel, fertiliser and plastic costs stemming from the Middle East conflict.
The National Accounts measure of domestic prices increased by 0.8 per cent in the quarter, with annual growth at 3.1 per cent. This was an acceleration from 2.9 per cent in the previous quarter, reflecting increased input costs stemming from higher oil prices. Rent and food drove consumption prices higher, but the rate of growth was somewhat restrained due to the temporary fuel excise reduction, a stronger Australian dollar and weak travel demand. Domestic inflation is expected to remain under upward pressure due to rising fuel costs and limited spare capacity in the economy.
After declining in the previous quarter, international prices rose sharply by 3.5 per cent in the June quarter, reflecting global market conditions and exchange rate movements. Over the year, international prices were up 3.8 per cent. Geopolitical and trade uncertainties continue to pose risks to the inflation outlook.
Business investment remained elevated, supported by ongoing data centre investment
Private investment was unchanged in the June quarter, making no contribution to GDP growth. Over the year to June, private investment was 8.4 per cent higher, down slightly from 8.5 per cent in the March quarter.
Business investment fell by 0.5 per cent in the June quarter, driven by lower investment in data centres following strong growth in the March quarter. Over the year business investment was 10.4 per cent higher, reflecting ongoing investment in data centres, with investment in machinery and equipment 15.9 per cent higher. Business investment as a share of nominal GDP fell slightly to 12.9 per cent and remains below the long-run average of just under 15 per cent.
Capital expenditure intentions for 2026-27, which is a leading indicator of business investment, were $201 billion, which is 14.9 per cent higher than the same reading for 2025-26. This strong increase was driven by non-mining capex plans, which rose 18.5 per cent, supported by continued investment in data centres and renewable energy projects. Mining capex expectations were 6.6 per cent higher compared to the same reading in 2025-26. It is worth noting that this measure is in nominal terms, which includes the impact of rising costs.
Government consumption offsets weakness in public investment
Public demand remains elevated as a share of the economy at 28.9 per cent. A strong pipeline of infrastructure projects and sustained demand for government services is expected to support activity over the period ahead.
Public demand increased by 0.2 per cent in the June quarter, contributing 0.1 percentage points to GDP growth. Growth was driven by government spending on services, with government consumption contributing 0.1 percentage points to growth, while public investment detracted 0.1 percentage points from GDP.
Government consumption grew by 0.6 per cent in the quarter and was 2.0 per cent higher over the year. Spending by both the Commonwealth and state governments remained supported by demand for health, aged care and other public services, while defence spending fell.
Public investment fell by 1.3 per cent, reflecting declines across general governments of all levels, with only Commonwealth public corporations experiencing strong growth. In annual terms, public investment increased by 2.4 per cent, up from 0.8 per cent in the March quarter.
Summary
Australia’s economy was patchy in the June quarter, supported by strong investment, rising EV purchases and solid commodity exports. But weak productivity and rising costs are keeping inflationary pressures elevated. These results are unlikely to ease Reserve Bank concerns, with capacity constraints and higher energy prices continuing to pose risks to the outlook. The key challenge is turning investment in AI, digital infrastructure and energy-efficient technology spending into stronger productivity and sustainable growth. This could be aided by further movement on the Government’s productivity agenda.