Ask most management teams what AI means for their business and the answer comes back in the language of cost: fewer people, a lower cost to serve, a productivity dividend. But an economy’s workers and its customers are the same people: for a business, the impact shows up on income statements, but for the economy, it shows up in consumer demand, which in the aggregate tends to hold even as the spending may shift.
A firm can read one correctly while misreading the other. A firm that automates its own labor while its customers are also in cohorts being automated elsewhere will compound its exposure. It will capture cost-savings while also experiencing weaker demand. And while the overall economy nets these effects out, a single business cannot.
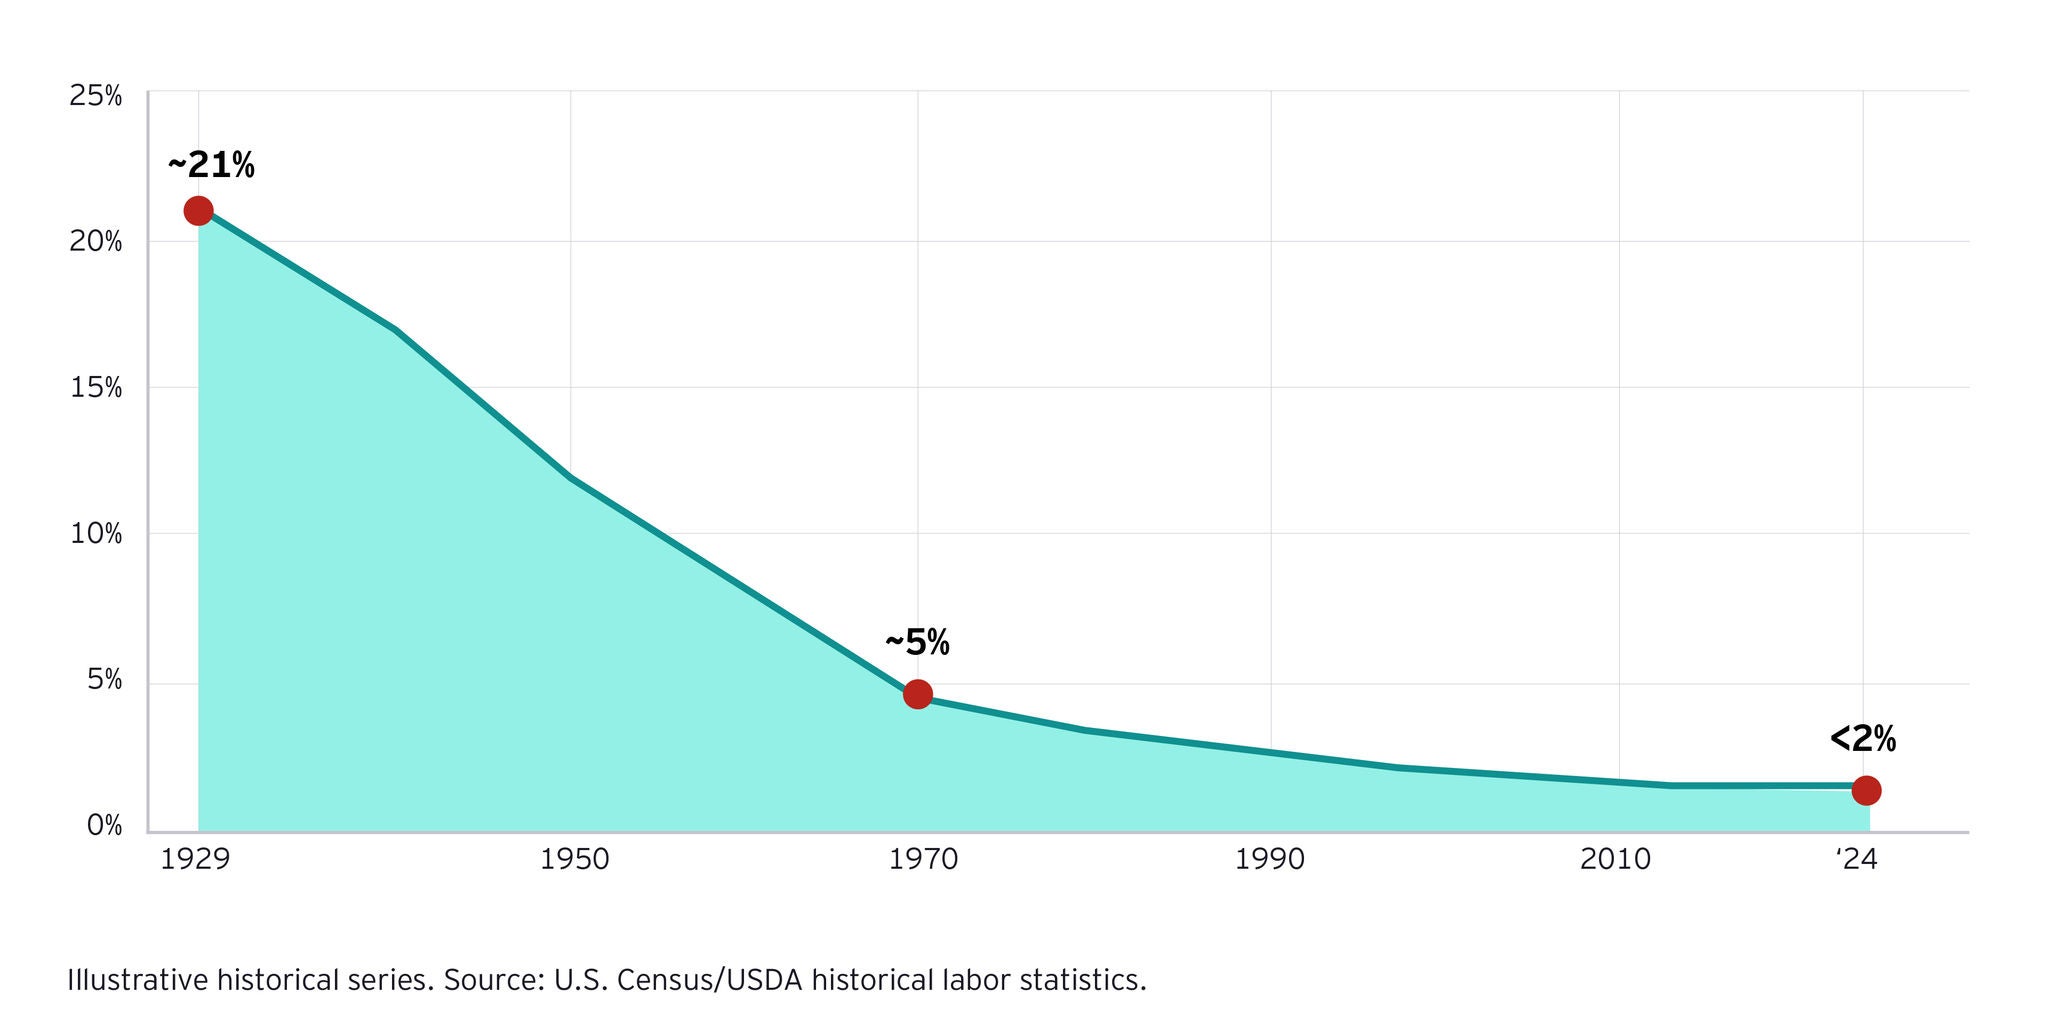
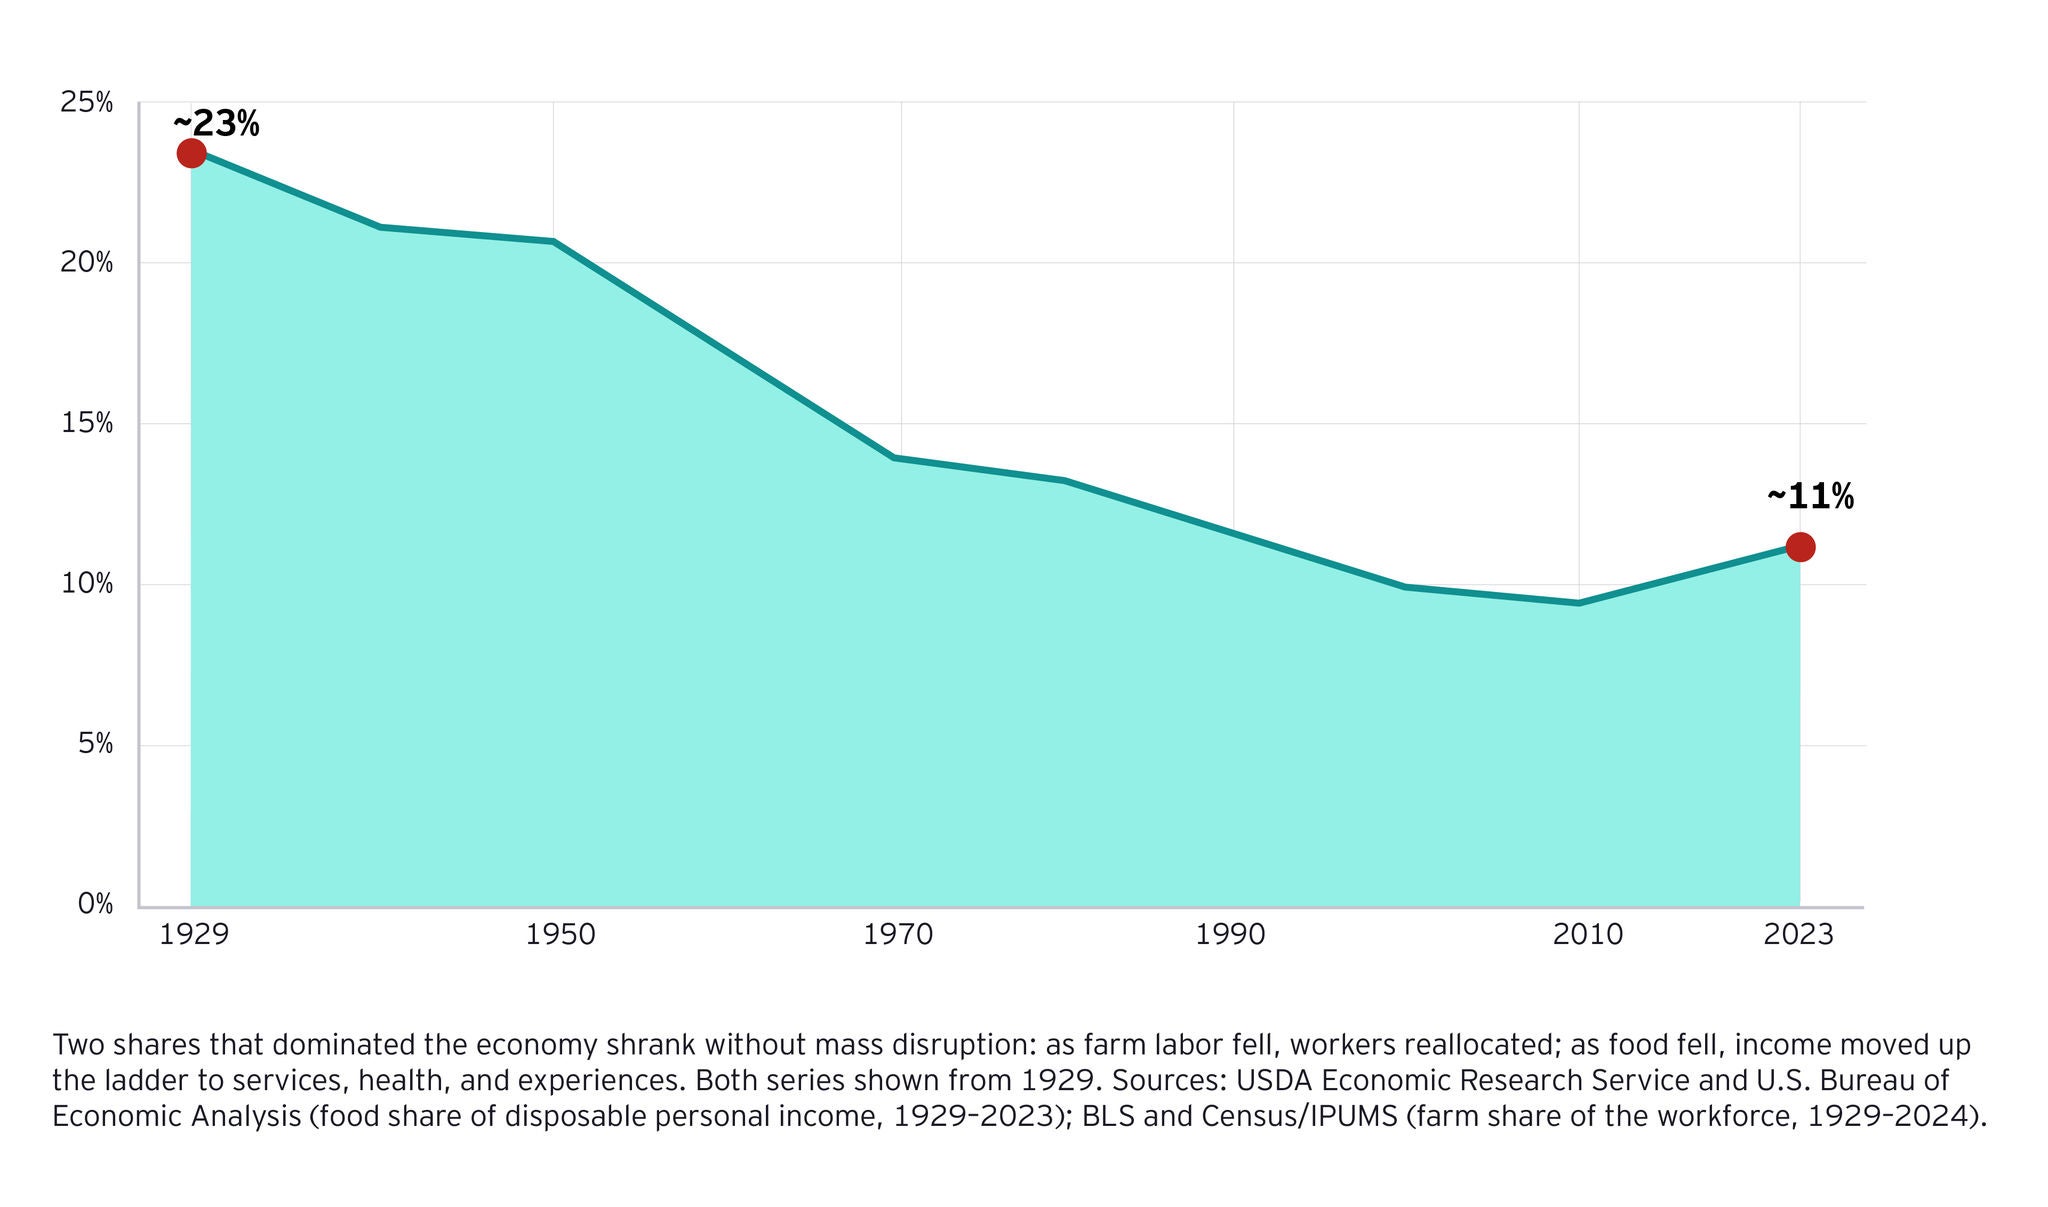
Meanwhile, restructuring a role requires additional expenditure, which complicates the potential downstream impact on demand. Where the incentive is strong, though, the reorganization begins, and it reorients not only how much a household spends but in what it buys. Better-paid workers in enriched roles allocate their new income toward travel, dining out, premium experiences and status goods, a typical impact as people grow richer. Those whose pay is compressed trade down toward necessities and value substitutes. The composition of demand may change dramatically within the most affected cohorts even if the total remains the same.
Separately, AI will impact production costs. Reduced costs can reach customers as a lower price, lifting real incomes and freeing spending, but only where competition forces the pass-through. In our experience, not all of the value of a cost decrease reaches the consumer, especially where firms hold pricing power and keep the saving as margin for shareholders rather than shoppers. And even where price does fall, the effect depends on how buyers respond: elastic demand turns cheaper prices into large new volumes and expanding output, while inelastic demand barely moves, and the saving is simply spent elsewhere.
No firm automates in a vacuum. Even a company content with its cost base can have its hand forced the moment a rival moves first: the early adopter lowers its unit costs and can then either undercut on price to take share or hold price and outspend everyone else on growth. Either way, the rest must follow or watch their margins and their customer bases erode. This is how entire industries may reset: competition turns “could automate” into “must automate,” drives cost out across the sector, and passes much of that saving through to customers as lower prices. The same pressure that squeezes a workforce is therefore what ultimately hands the saving to the consumer and sets the demand reallocation in motion.
Between them, these two paths decide whether a productivity gain returns to customers as higher real incomes and shifting demand or ends up retained as margin while some jobs compress.