EY refers to the global organization, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients.
Recent Searches
EY State of Consumer Products 2026 report
Supply chain complexity is a growth advantage for those consumer product companies able to identify and serve demand profitably at pace.
New updates now available
The latest edition of the State of Consumer Products report is here. Get your copy today to learn how CP supply chains can help drive growth.
Relevance at speed: turning supply chain complexity into growth advantage
Growth in consumer products (CP) requires companies to address smaller, faster-moving and more complex and harder-to-serve demand pools. These shifts are influenced by digital platforms, retailer dynamics, changing consumer behavior and AI-enabled decision-making. For large CP companies, the capabilities that built advantage for decades — scale, efficiency and broad distribution — remain important, but they are no longer sufficient on their own.
Organizations must manage supply chain complexity at speed to remain competitive. The question for leaders is no longer whether complexity can be removed, but:
- Which complexity creates value?
- How quickly can the business respond in real time?
- Can growth be captured profitably, without losing control of cost, service, margin or risk?
EY teams, in collaboration with Oxford Economics, surveyed more than 850 senior executives across 24 markets to understand how CP companies are transforming their supply chains, operating models and decision-making. The research also benchmarks the progress of CP companies across key dimensions of supply chain transformation.
Key takeaways:
Growth is becoming harder to find and harder to serve profitably. This report gives CP leaders’ perspectives on how to turn supply chain complexity into a source of profitable growth:
- Understand how growth is shifting toward fragmented demand.
- Identify which complexity creates value versus cost.
- Recognize how supply chain performance influences demand.
- Enable faster decisions with AI and the right supply chain operating model.
- Drive advantage by balancing velocity, precision and economic discipline.
- Align people, process, technology and trust in transformation.
Why growth in consumer products is shifting
Growth in CP is becoming more granular. Mega and medium-sized brands still drive most category sales, and private label remains steady competition, but smaller brands are gaining momentum.
Most supply chains are still optimizing, not redesigning
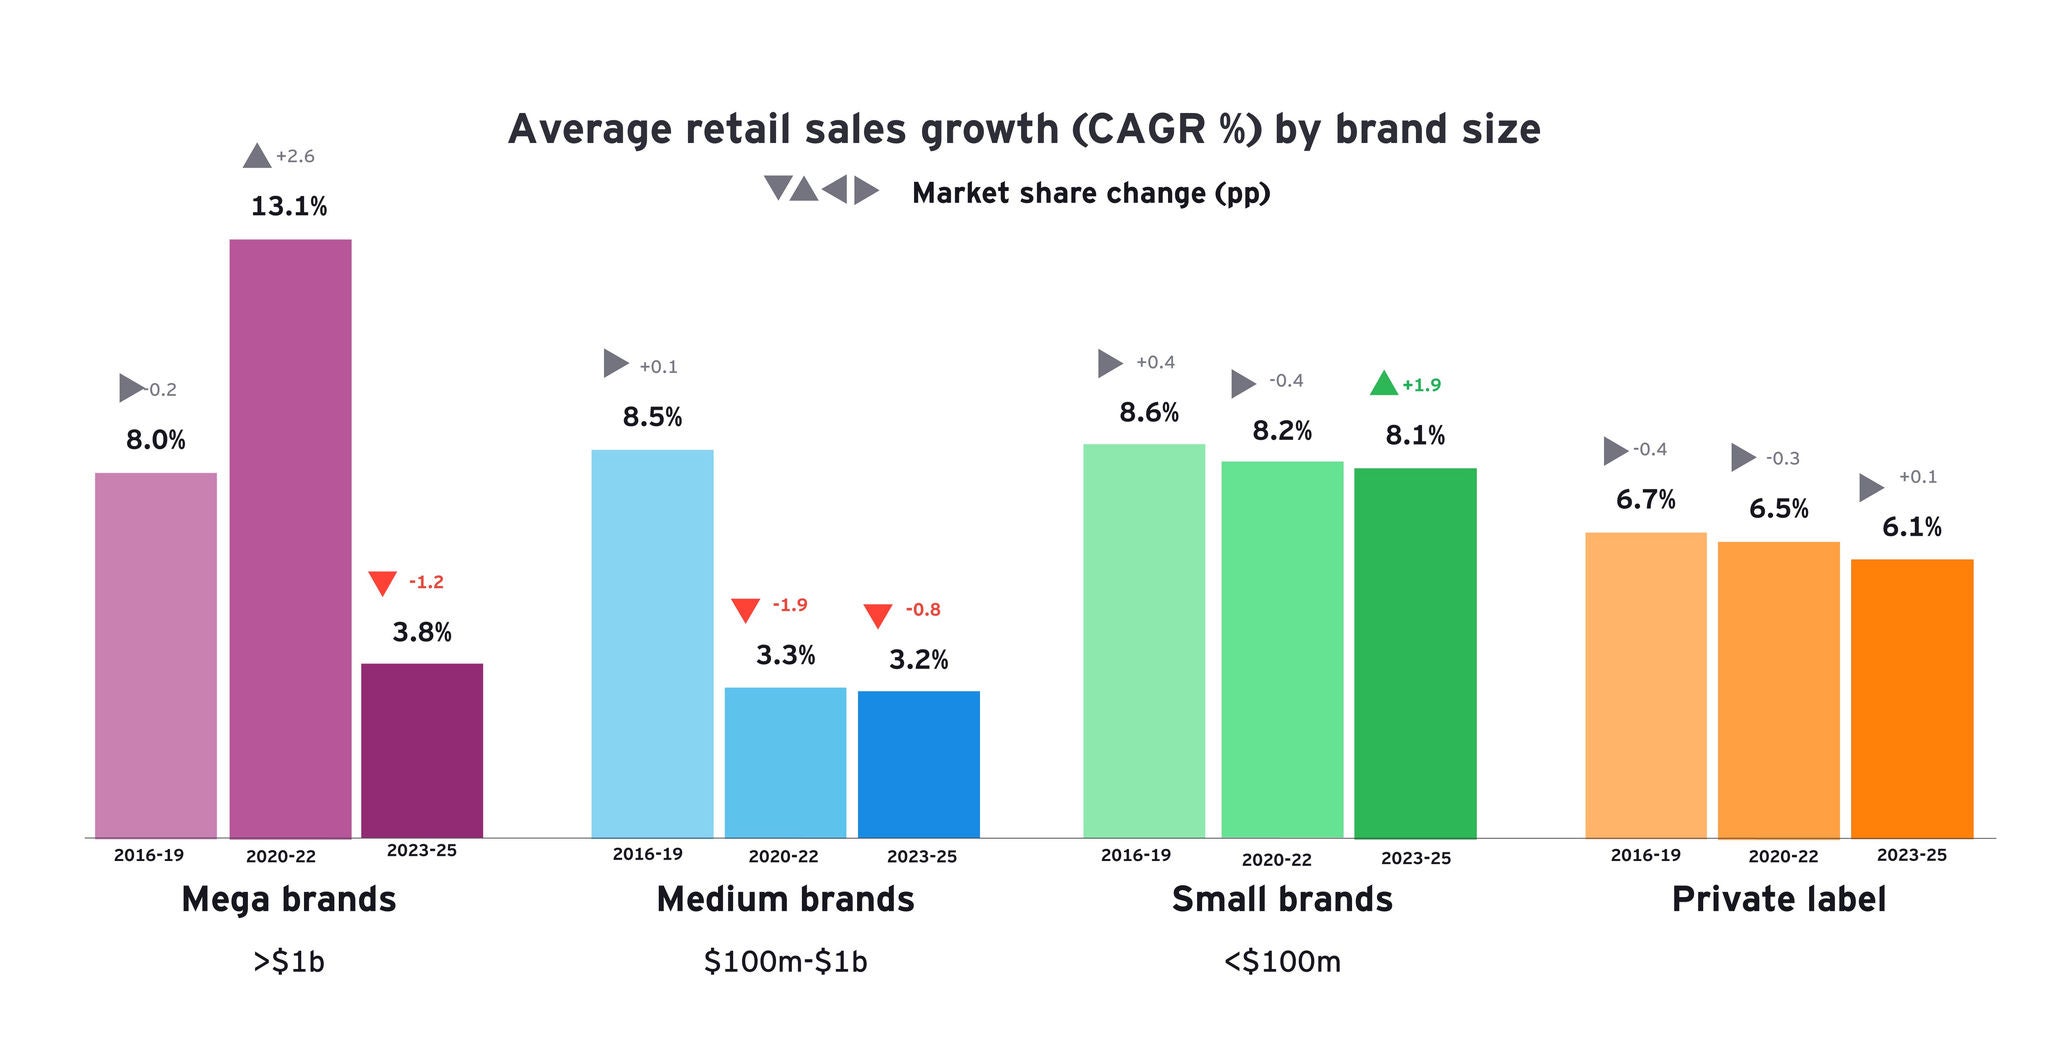
Source: EY Insights Analysis; Euromonitor International
Footnote: Analysis covers >6,000 brands across alcoholic beverages, packaged food, beauty and personal care, home care, pet care, and soft drinks. Growth measured as CAGR of retail sales price (RSP); market share reflects each segment share of total RSP sales.
Arrow labels show market share change in percentage points (PP); gain (>0.5 pp), broadly flat (±0.5 pp), loss (<-0.5 pp).
Consumer needs, channels and shopping occasions are becoming more fragmented, meaning CP growth strategies must be more precise about where to play and how to serve. The companies that are better placed to pull ahead will be those that build the capability to serve complexity selectively, move on it quickly and control it economically. They will know which opportunities are worth serving, respond before competitors and maintain economic discipline as they do so.
How supply chain now shapes demand
Supply chain is taking a larger role in delivering the brand promise, increasingly becoming part of how demand is shaped. Availability, product data, fulfillment reliability and substitution risk can shape whether a brand is recommended, substituted or ignored. As a result, portfolio decisions made on volume or gross margin alone are no longer sufficient. Some products may have weak financials but strengthen baskets, loyalty or retailer relevance. Others may appear stable while consuming disproportionate operational effort.
Finding value in supply chain complexity
With the biggest opportunities increasingly emerging in smaller, faster and harder-to-serve demand pools, the complexity and variation that supply chain operating models were designed to remove are now where relevance and value live. Successful companies will be able to distinguish between supply chain complexity that creates value and complexity that destroys it (by consuming capacity, capital and attention).
Putting a price on supply chain complexity — does it add value or cost?
|
Bad Complexity |
vs |
Good Complexity |
|---|---|---|
|
Unnecessary park or packaging variation |
Channel-specific propositions |
|
|
Overlapping SKUs |
Premiumization |
|
|
Fragmented specifications |
Regional relevance |
|
|
Low-value line extensions |
Rapid trend participation |
|
|
Operational duplication |
Differentiated propositions |
|
|
Inefficient manufacturing requirments |
High-value consumer missions |
Why supply chain operating models are the constraint
CP companies have more visibility over demand movement, customer pressure, channel variation, portfolio complexity and operational risk – that’s a lot of signals to act on. But turning insight and visibility of the signal into fast, coordinated and economically controlled action requires new ways of working. Too often there is too much rigidity in the system, whether that’s physical (manufacturing is where complexity becomes real), planning (decisions wait too long) or in decision-making (where hand-offs lose growth) to capitalize on the opportunity.
EY research on supply chain maturity shows the majority of companies are on a transformation journey but are focused on improving and optimizing the current model rather than redesigning it.
Supply chain maturity – optimization to redesign
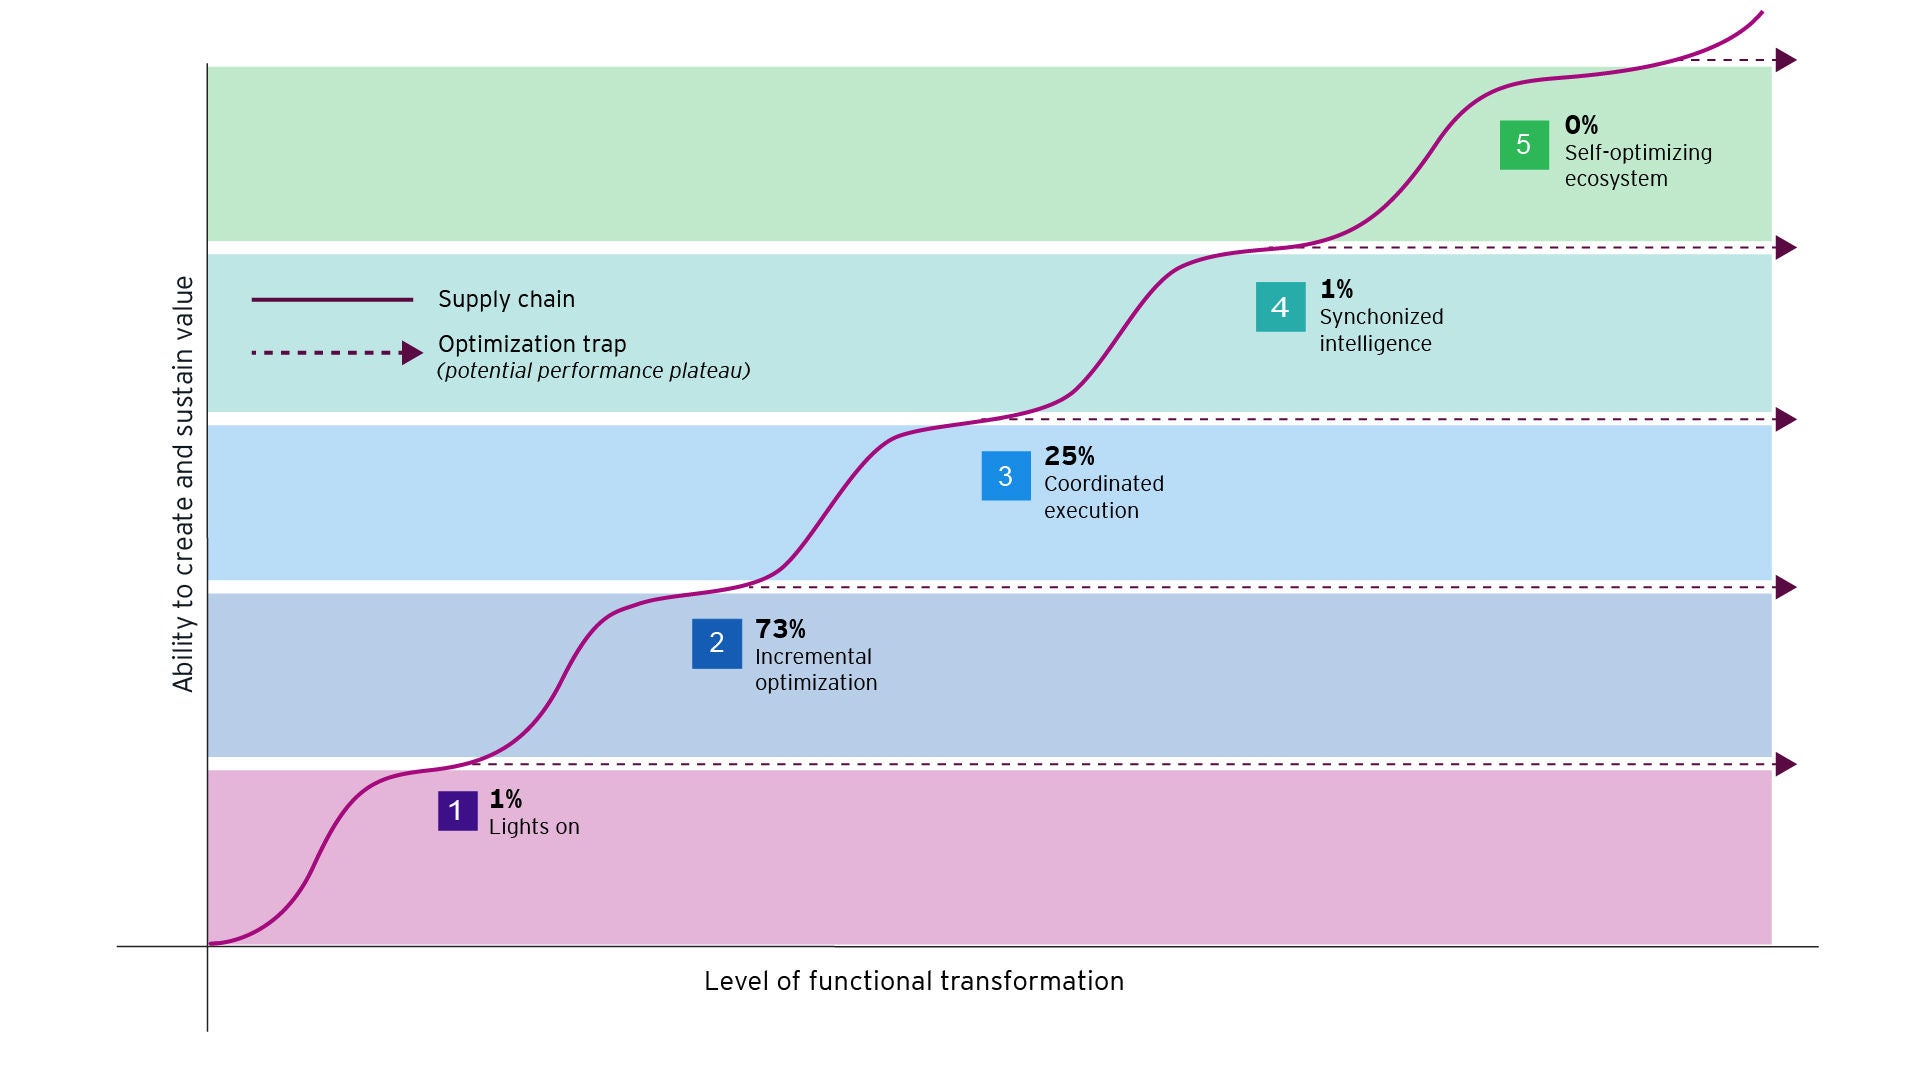
Source: EY Consumer Products Dynamics Research 2026
|
Lights on |
Incremental Optimization |
Coordinated Execution |
Synchronize Intelligence |
Self-optimizing Ecosytem |
|---|---|---|---|---|
|
Driving stability and business continuity |
Reducing operating friction and amplifying outcomes |
Executing consistent, data-enabled approach/outcomes |
Making better, future-looking decisions faster |
Enabling always-on ecosystem optimization |
|
Maintaining day-to-day operations, with teams working largely independently and relying on manual processes; some baseline data, reporting, and controls, however, decisions remain fragmented and largely backward-looking |
Building alignment across teams around shared priorities and key moments, improving coordination and increasing the use of data in decisions around common decisions, with decisions still negotiated function-by-function |
Establishing and executing against an integrated commercial plan with shared planning cycles and aligned priorities informed by data and platform insights to deliver consistent and aligned execution and decision making across teams |
Integrating data, systems, governance, and teams into a unified growth engine that connects insights, decisions, and execution to support faster, and more proactive and strategic forward-looking actions |
Operating as a connected, Al-enabled ecosystem that automates execution and emphasizes strategic stewardship and orchestration, continuously improving decisions and performance across internal org and external partners |
The longer companies optimize the current system without redesigning how decisions move, the greater the risk that they become highly efficient in the wrong part of the market. What’s really happening is that companies are changing supply chain tools faster than they are changing how the enterprise decides. Successful companies will increase manufacturing flexibility, rethink planning cycles, and connect fragmented decision-making, so they can act on opportunities faster.
AI will prove to be a great enabler, able to read a wider set of signals in real time, improving sensing and decision support. But it does not work in isolation – it cannot resolve unclear ownership, weak governance or slow execution increases. CP companies will need to put solid foundations in place, so more intelligence leads to more value creation. The real risk for companies is less that they underinvest in AI and more that they adopt AI inside an old model.
What leading CP companies are doing differently
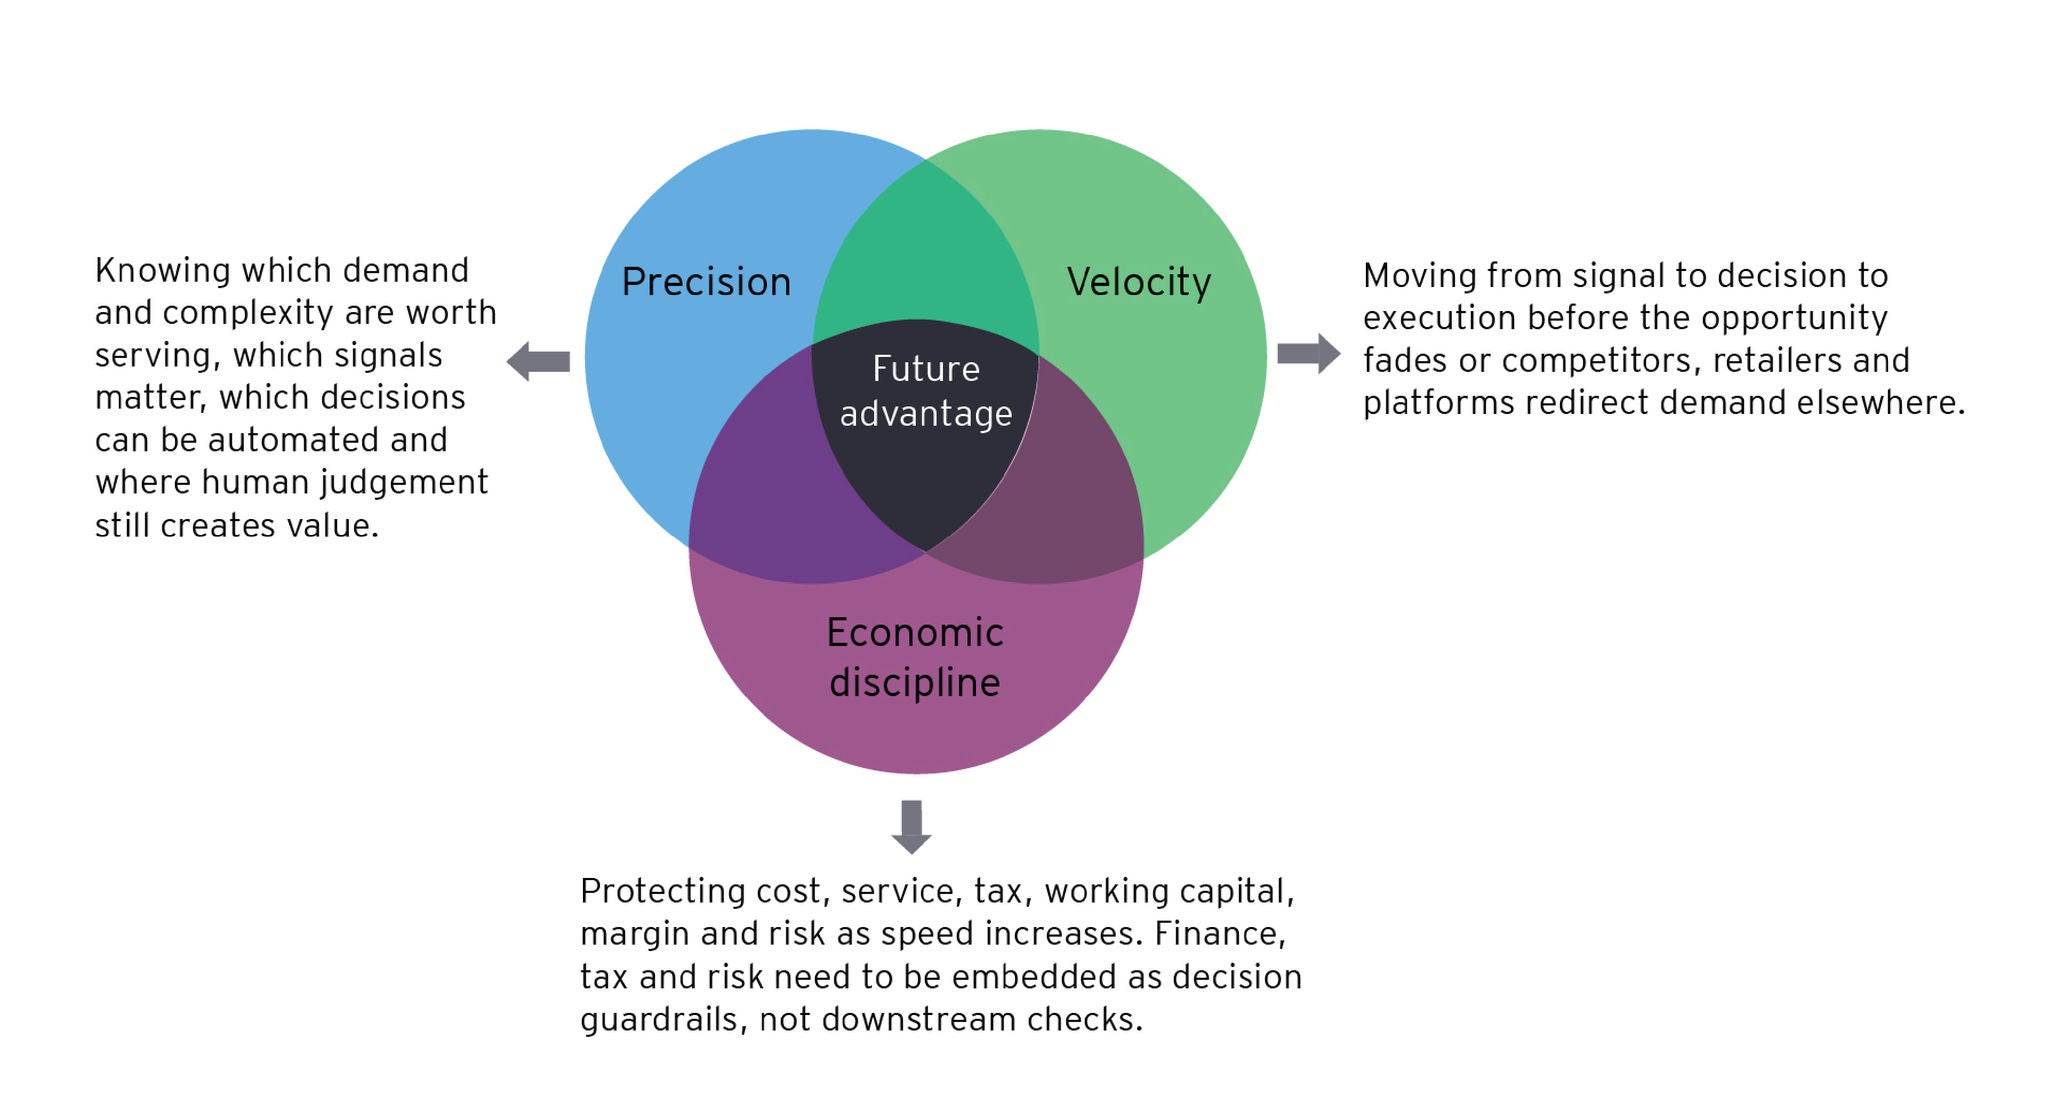
Future advantage will come from knowing which hard-to-serve supply chain complexity creates value, what to simplify and how fast the business can move without losing control. It depends on how effectively organizations balance velocity, precision and economic discipline. Velocity without precision creates inefficiencies, while precision without velocity creates missed growth. Both, without economic discipline, create unprofitable complexity.
Future advantage lies at the intersection of velocity, precision and economic discipline
As supply chains are increasingly recognized for their contribution to brand promise and selection, they’re becoming engines of growth and competitive advantage in their own right. Strength will lie in their ability to connect the end-to-end value chain – from growth strategies, innovation and product development through planning, sourcing, manufacturing, logistics and customer fulfilment – and establish integrated decision-making across the enterprise.
How EY can help
-
Addressing an organization’s overarching end-to-end supply chain and operations strategy to grow, optimize and protect their operations.
Read more -
Our Commercial Excellence team helps Consumer Products (CP) companies drive brand and channel strategy to RGM and execution excellence. Learn more.
Read more -
EY Studio+ helps you deliver unique customer experience (CX), using empathy and purpose and adding lasting value to customers, your business and society.
Read more -
EY’s Transformation Platforms, a unique combination of EY know-how and proprietary digital tools, can jumpstart your transformation journey. Learn more.
Read more -
Read more
-
The EY Enterprise Resilience solution helps organizations navigate disruption with agility — reducing risk and driving long-term value. Learn more.
Read more -
The Geostrategic Business Group can help translate geopolitical insights into business strategy to help manage political risk. Find out how.
Read more -
A smart platform accelerating innovation with consumer driven insight, qualification and rapid market readiness.
Read more
The State of Consumer Products report authors
Richard Taylor
EY Global Consumer Products Sector Leader
Thomas Pyschny
EY Global PLM Innovation Excellence Leader; EY Europe West Consumer Products Sector Leader
Lokesh Ohri
EY Americas Consulting Consumer Products Leader
Andrew Cosgrove
EY Global Insights Leader
Umar Alizai
EY Americas, US East, Supply Chain and Global Trade Integration Lead
Jocelyn Hallum
UK Supply Chain transformation Leader and Planning & PLM Solution Lead
Jon Garbutt
Partner, Supply Chain Consulting, Ernst & Young LLP
Matthew Burton
EY EMEIA Supply Chain and Operations Leader