EY refers to the global organization, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients.
Recent Searches
Technology services: Deal insights series H1 2026
Comprehensive analysis of deal activity in the technology services vertical in H1 2026 across key sub-markets.
Tech services: Deal insights series H1 2026
Deal insights series 2026
Technology services M&A activity remained active in H1 2026 despite softer discretionary demand, macroeconomic uncertainty and AI-led disruption to traditional delivery models. Geopolitics, oil prices and inflation further weighed on IT spending, making growth elusive for many IT services players and prompting providers to pursue inorganic growth. The market operated at two speeds: well-capitalized strategic buyers pursued large deals for scale, geographic expansion and enhanced vertical capabilities, while private equity focused on selective consolidation of niche businesses and value-driven opportunities for their portfolios across the US and Europe.
- Deal activity remained resilient, but disclosed value was concentrated in a few headline transactions. The seven largest deals contributed approximately US$10.3 billion, highlighting an active but increasingly selective market in which buyers prioritized value assets, sharper underwriting and reasonable multiples.
- At least 10 transactions with disclosed deal values exceeding US$300 million were announced in H1 2026, demonstrating continued appetite for scaled assets where the strategic logic was clear. AI shaped acquisition narratives, but client access, industry credibility and scale remained the assets changing hands. As standalone AI capabilities become more accessible, buyers increasingly value businesses combining scale, vertical depth and ecosystem positioning to participate in large enterprise AI transformation mandates. This represents a shift from the 2019 to 2023 cycle, when boutique capability differentiation commanded a premium. The democratization of AI capabilities through open-source models, hyperscaler tooling, and the rapid diffusion of engineering knowledge has compressed the shelf life of standalone AI differentiation, making proprietary capability alone difficult to sustain as a long-term competitive moat.
- Acquisition interest also extended into the infrastructure supporting enterprise AI. Accenture expanded across cybersecurity and network intelligence through Dragos and Ookla, while Cognizant’s acquisition of Astreya added data center and AI infrastructure services. These areas provide exposure to AI adoption while retaining relevance beyond any single AI application.
- Data and analytics also remained active, with buyers increasingly focused on the Databricks ecosystem. Compute, data and analytics and cybersecurity are likely to be the most durable areas, as demand should persist regardless of which AI applications dominate. Training data carries a higher conviction risk, as better models and synthetic data may reduce reliance on human annotation.
- AI’s commercial impact is becoming more visible despite limited and inconsistent revenue disclosure. Providers are gradually exploring outcome-based and services-as-software models as AI productivity makes headcount-linked pricing harder to defend, although adoption remains early and uneven.
- Public market valuations moderated amid slower growth, prolonged decision cycles and uncertainty around AI-led disruption. EBITDA margins remained more resilient than revenue growth, although continued AI investments partly offset benefits from improved utilization and currency tailwinds.
Looking ahead, maturing private equity platforms and continued demand for vertical specialization are expected to shape deal activity. Healthcare and financial services should continue to attract buyer interest, as AI amplifies the value of domain knowledge in regulated sectors where institutional complexity and legal constraints matter as much as technology. However, AI capability alone is unlikely to command earlier-cycle premiums without scale, vertical depth or ecosystem positioning. Buyers are expected to favor a strong AI-era position where the underlying standalone economics remain sound.
Our latest M&A thinking
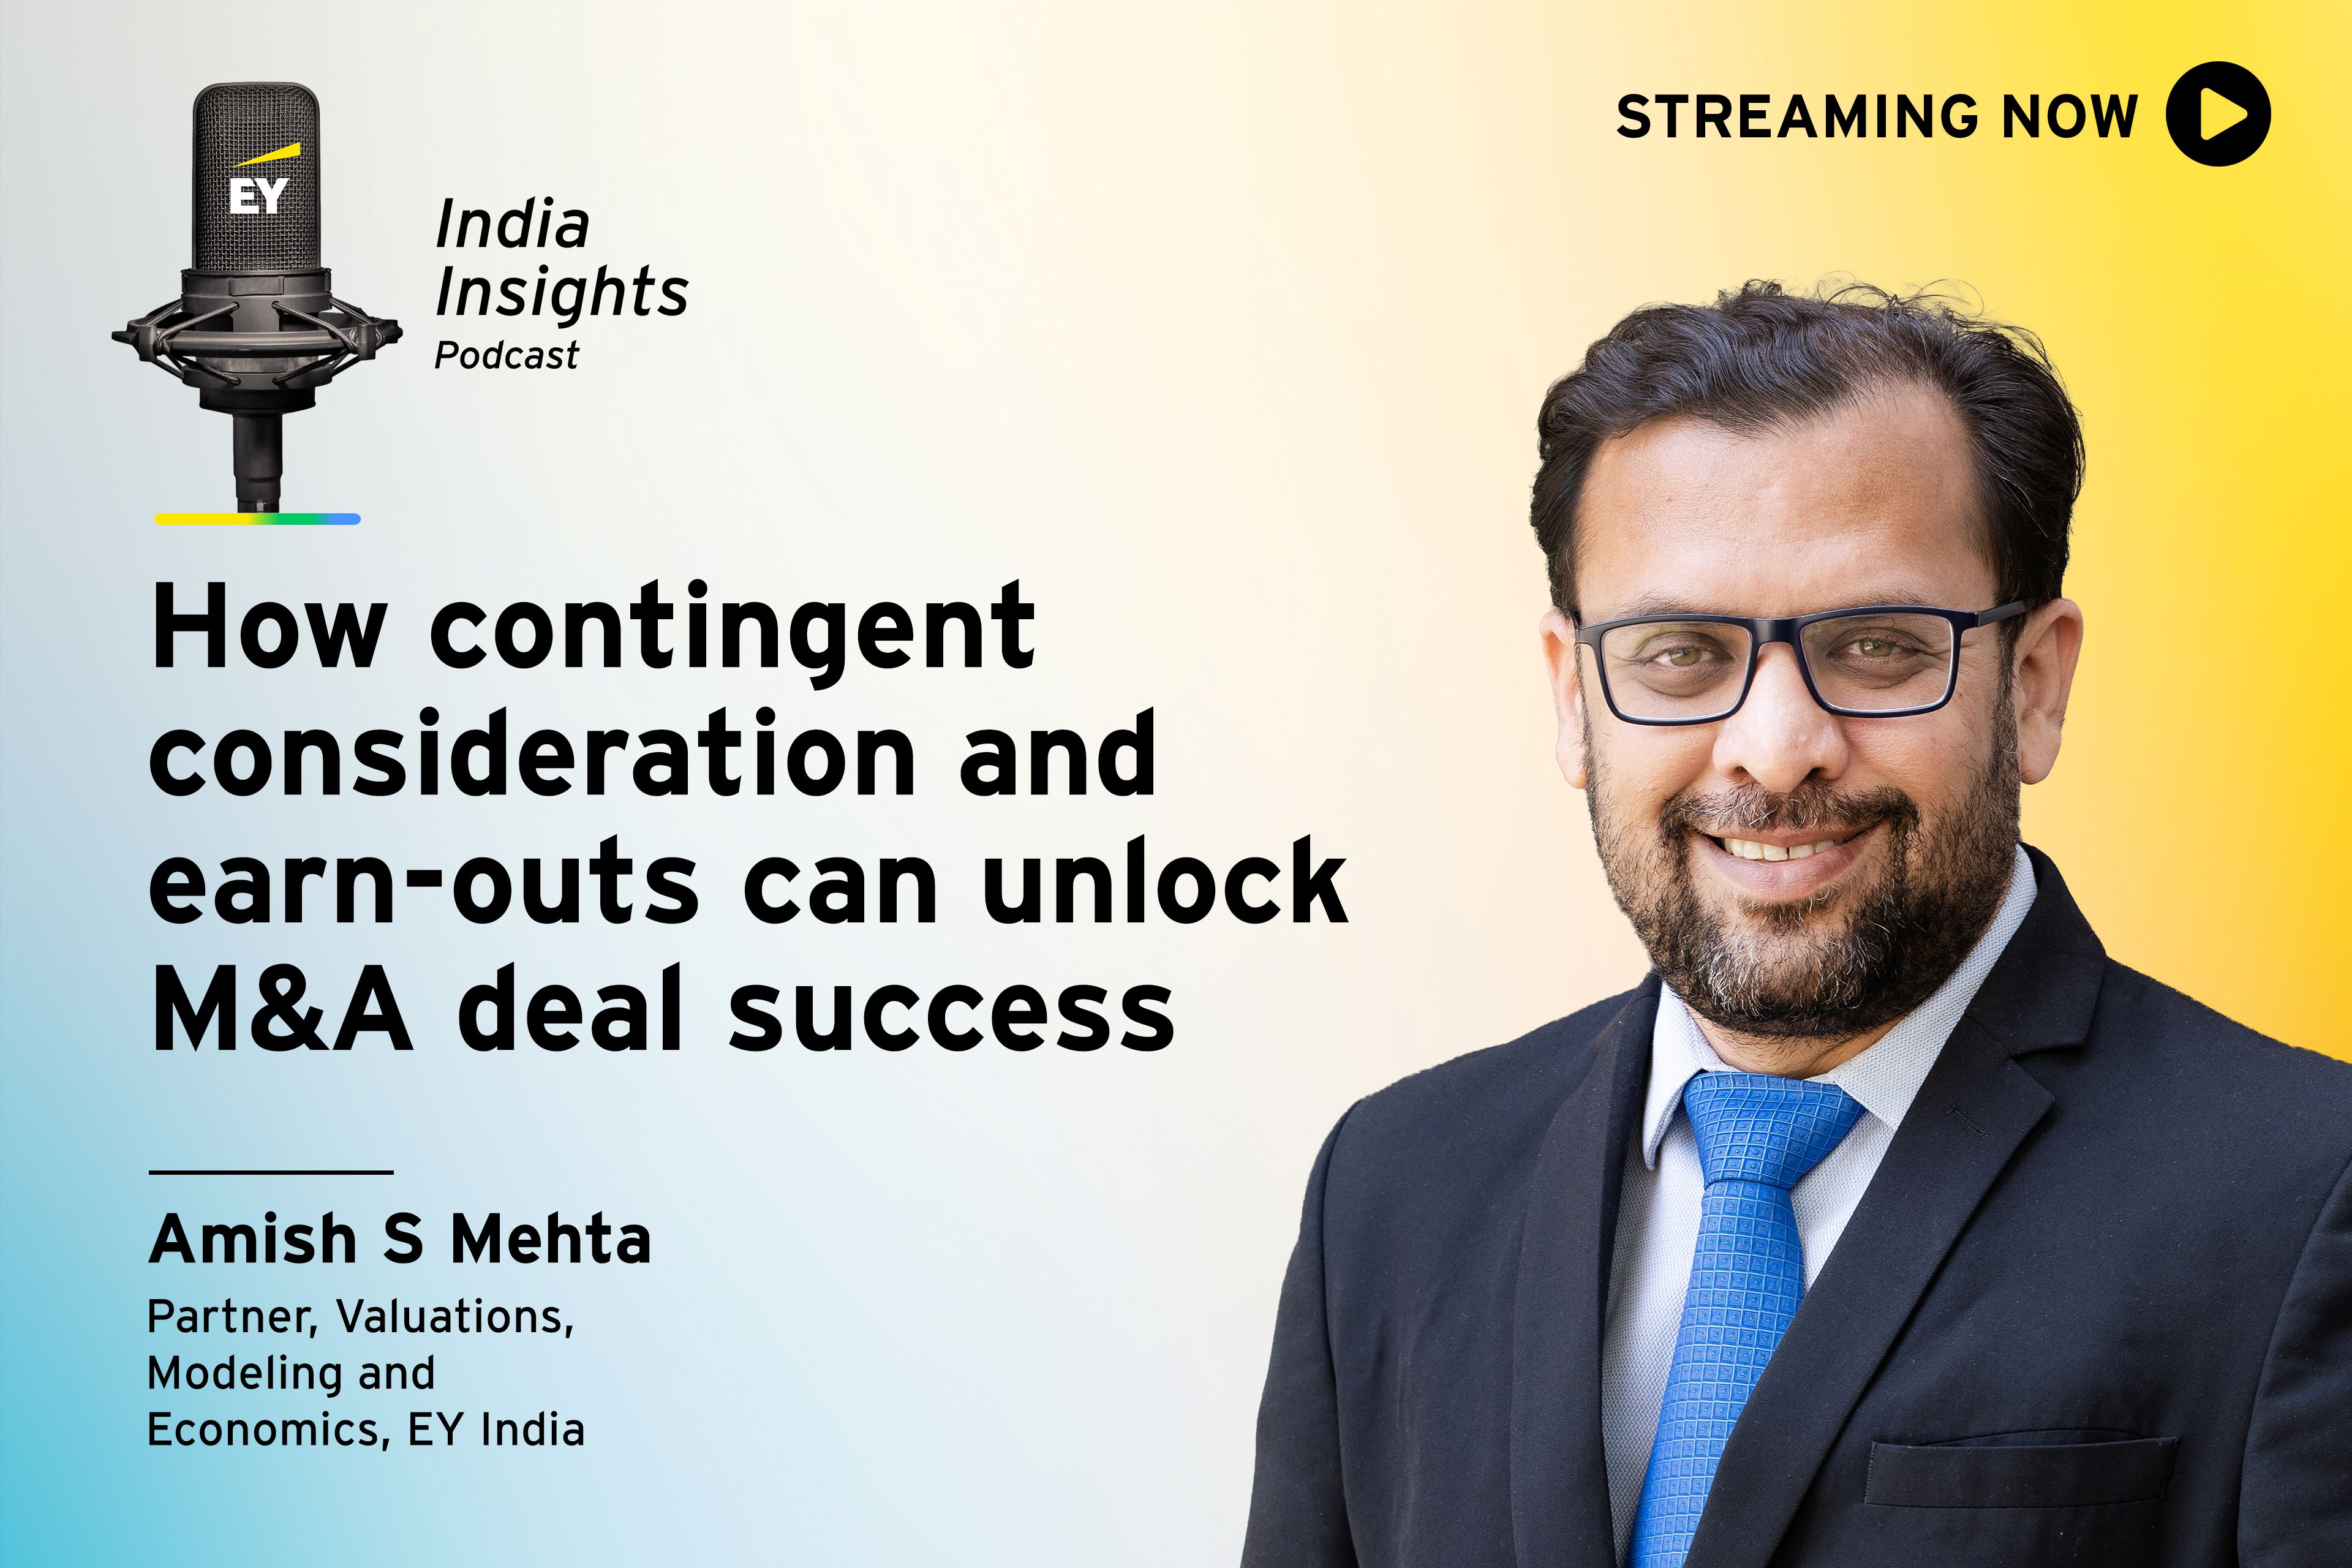
How contingent consideration and earn-outs can unlock M&A deal success
Tune in to the EY India Insights podcast as Amish S. Mehta shares how earn-outs and contingent consideration can bridge valuation gaps in M&A deals.
5m 40s
AI is redefining IT services, but earnings quality is the real test
AI is transforming the IT services economics. Learn why earnings quality, AI-driven diligence and sustainable value creation matter more than growth.
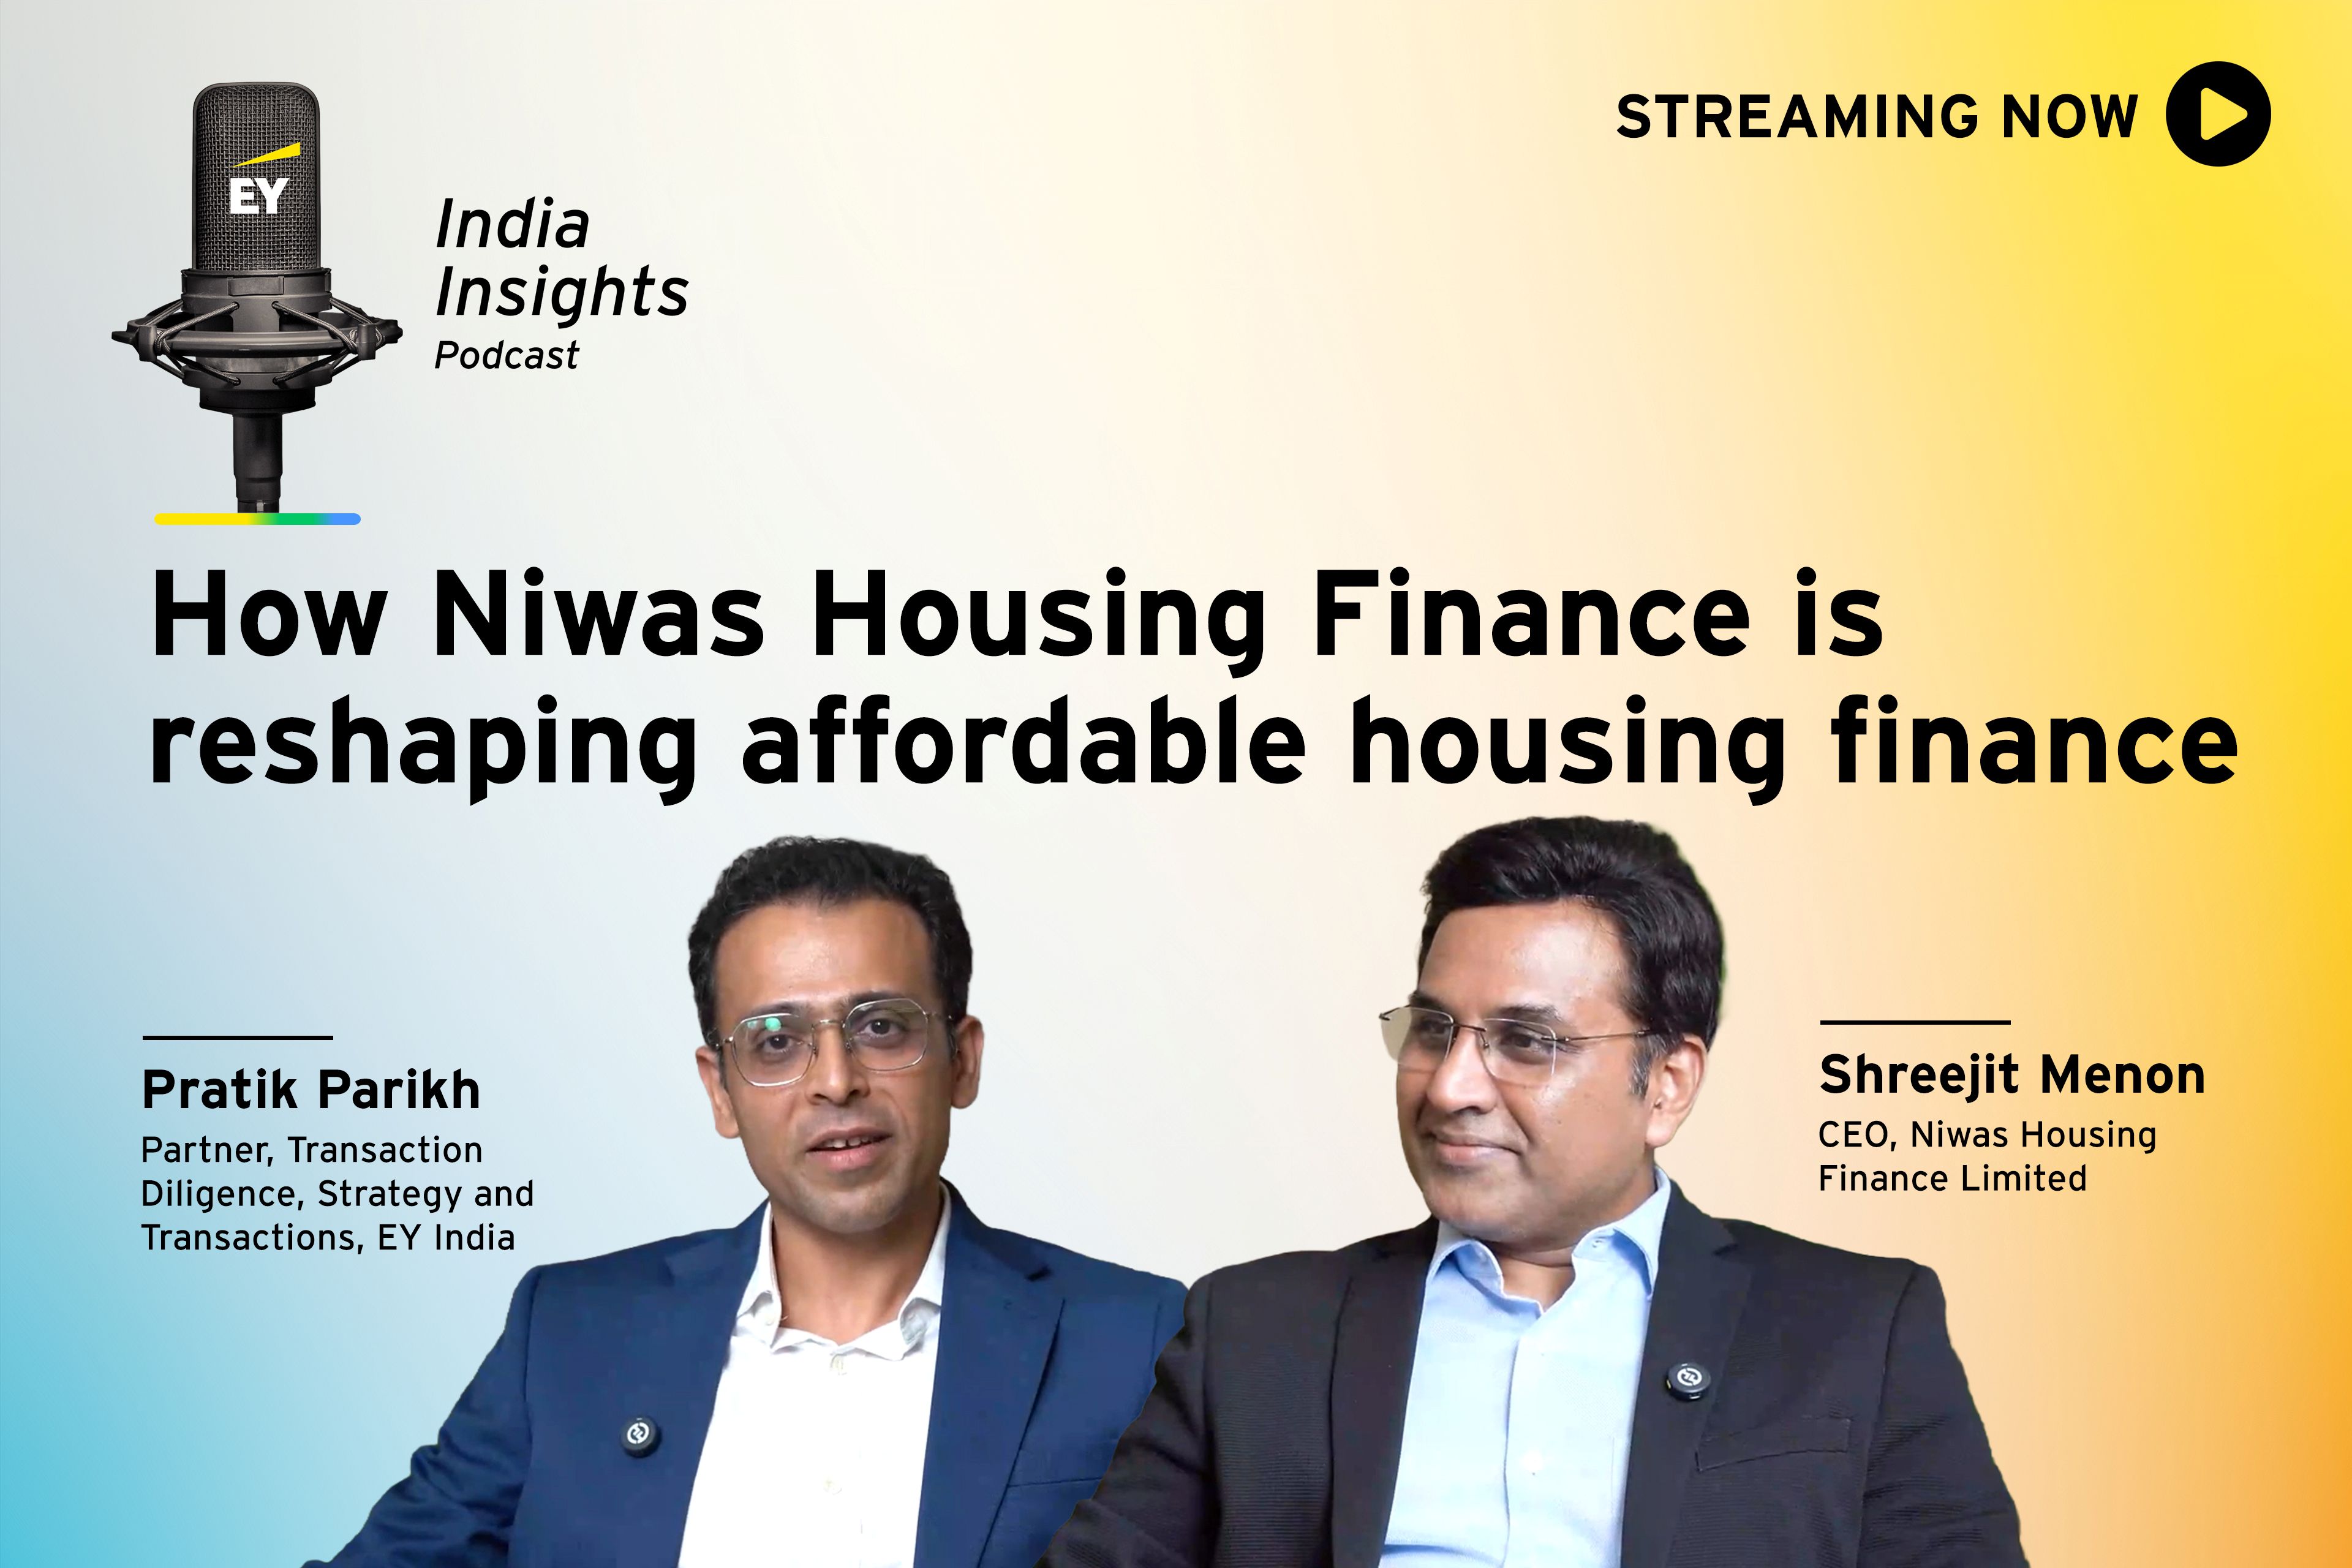
How Niwas Housing Finance is reshaping affordable housing finance
Tune in to the EY India Insights podcast as Niwas Housing CEO Shreejit Menon discusses housing finance trends, AI adoption, risk and growth strategies.
19m 25s
Contingent consideration for closing deals through earn-out structures
Learn how contingent consideration is valued using scenario-based and option pricing methods, and fair value accounting for earn-outs in M&A deals.
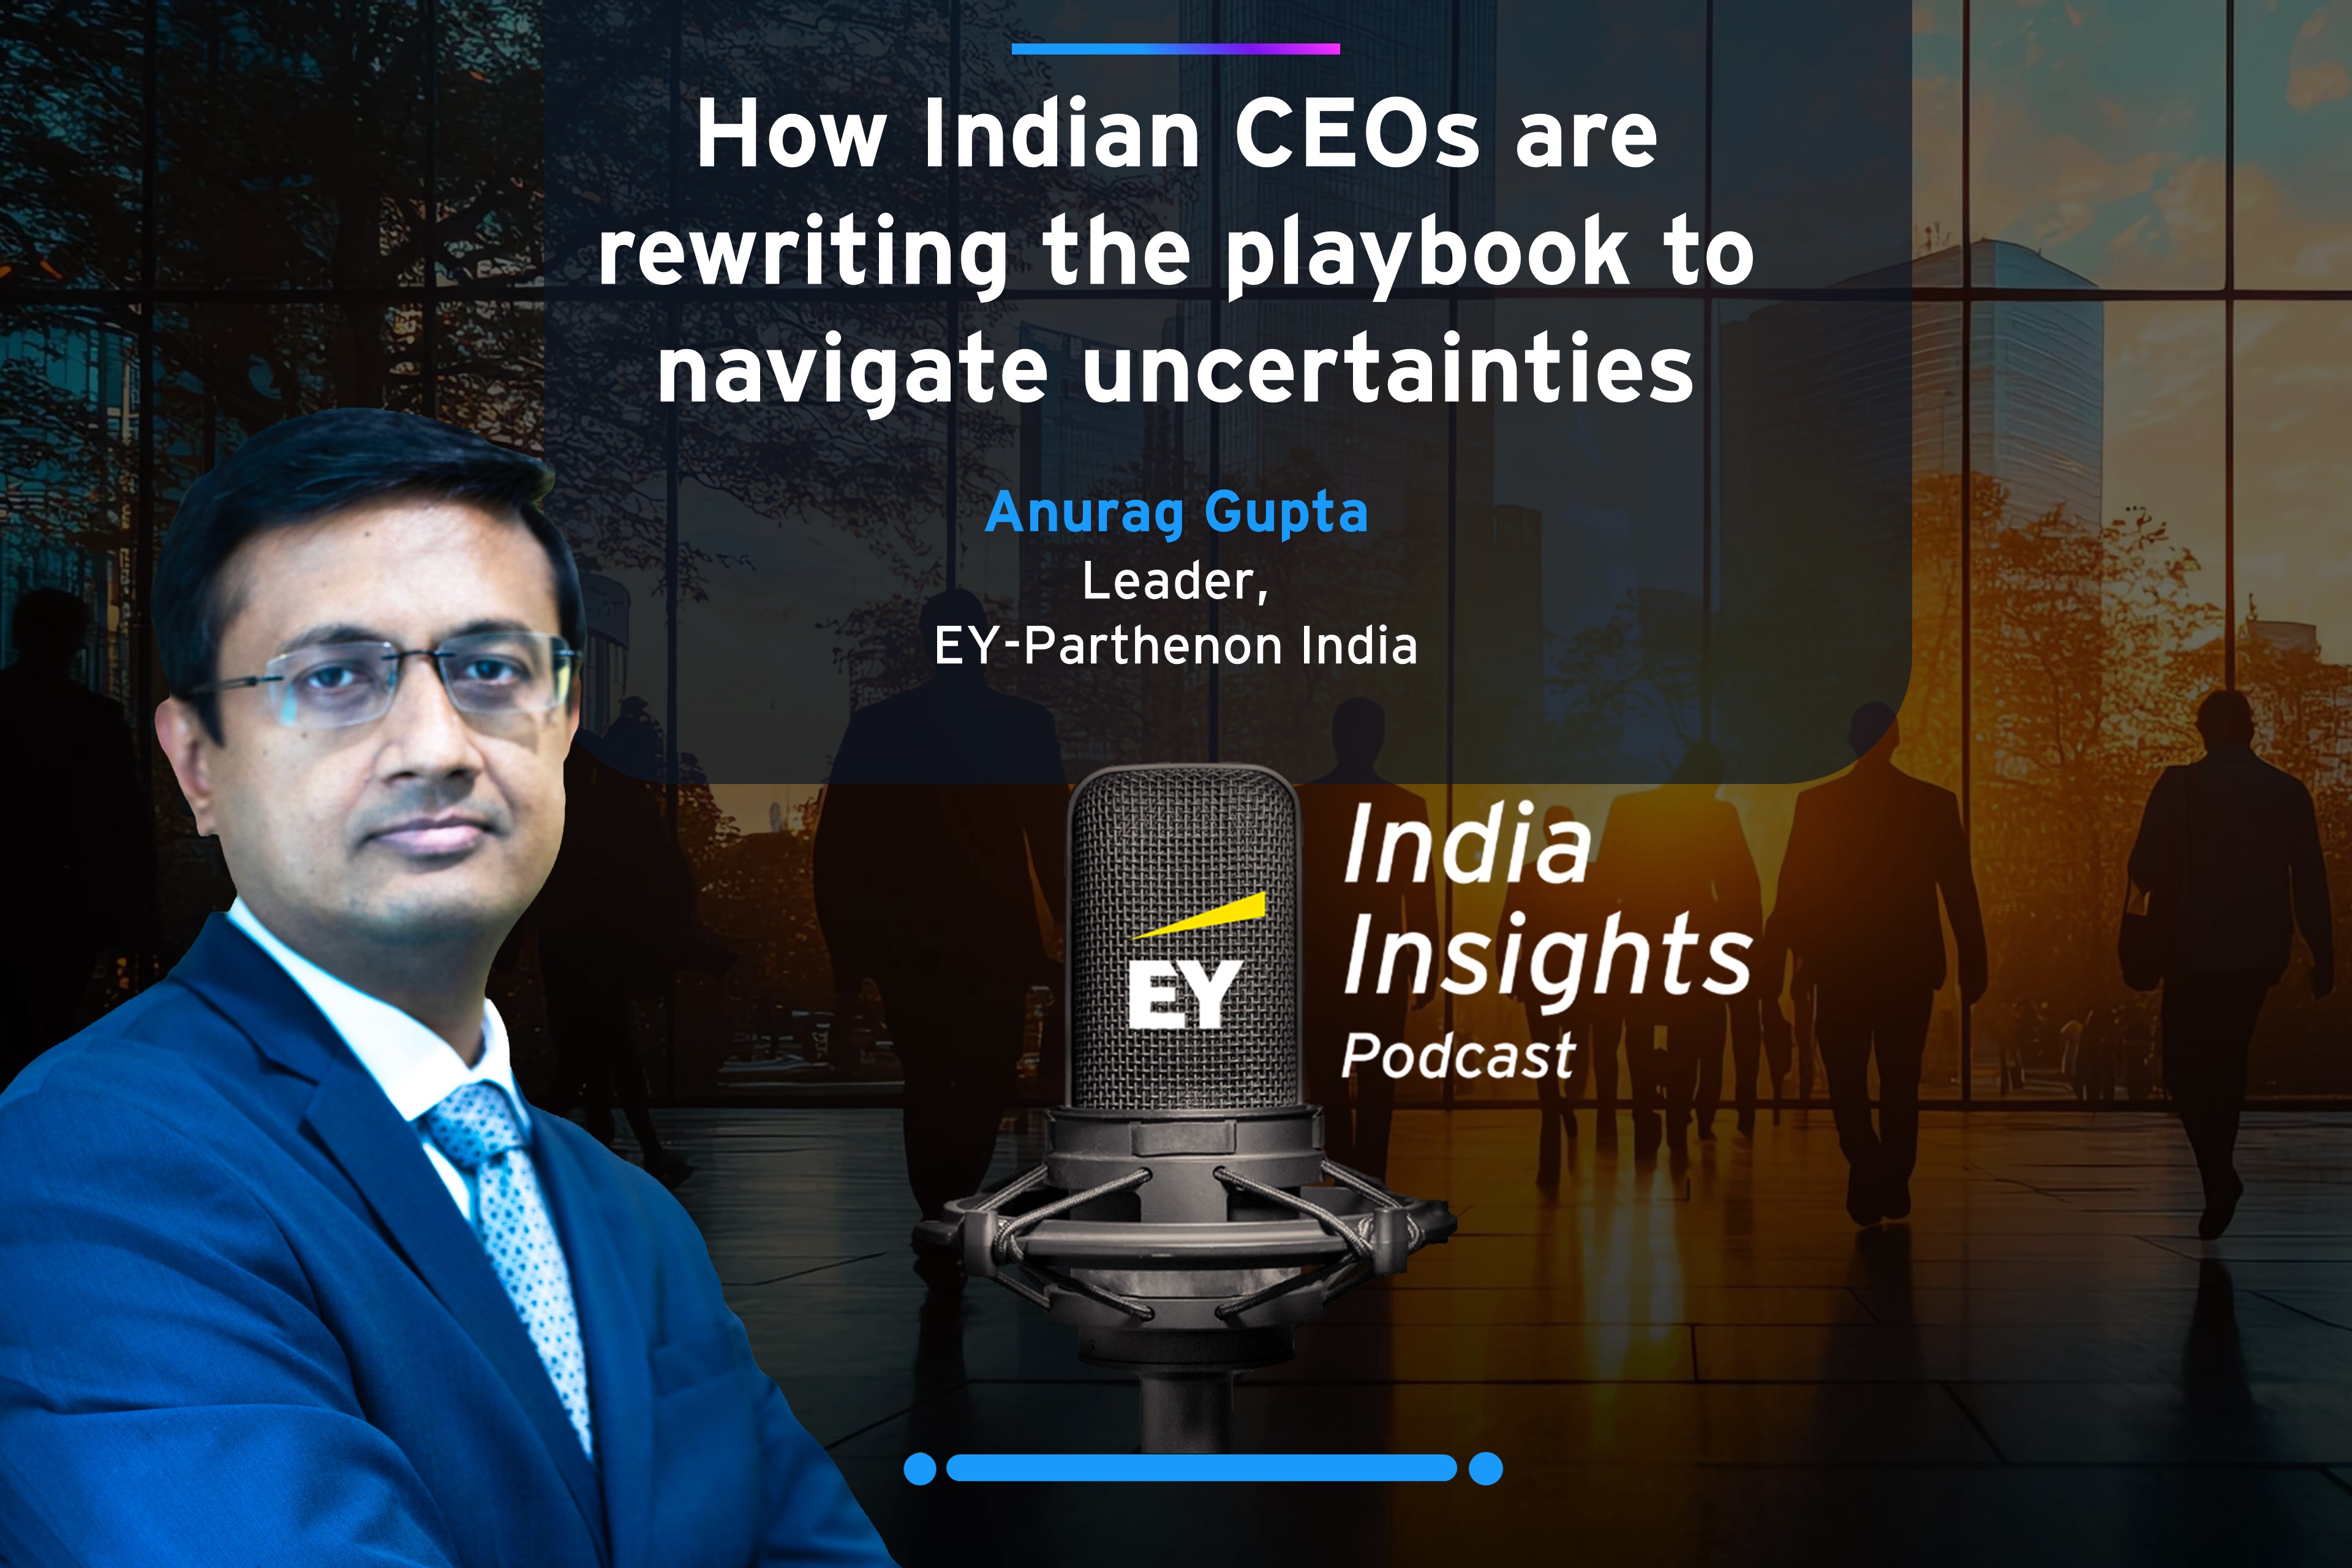
How Indian CEOs are rewriting the playbook to navigate uncertainties
Explore how Indian CEOs are resetting strategy amid geopolitical shifts, strengthening supply chains, embracing AI and driving growth.
15m 15s
IBC at 10: How India’s debt market has evolved
Explore how the Insolvency and Bankruptcy Code has reshaped India’s credit culture, boosted investor confidence and unlocked value in stressed assets.
24m 54s
How Indian CEOs are resetting strategy amid geopolitical fragmentation
Indian CEOs are resetting their strategy amid geopolitical fragmentation, using AI and discipline to drive resilient growth and long-term value.
How India is driving dairy value to lead the global market by 2047
India’s dairy sector must shift from volume to value through productivity, quality, infrastructure and export readiness to build global competitiveness.
Rethinking secondary transaction discounts in Indian start-ups
Secondary transactions in Indian startups rarely come at a discount, with most priced in line with primary rounds.
How selective investing shaped India’s M&A deals in 2025
India’s M&A in 2025 favored fewer, larger deals as value rose 18%. Infrastructure-led and cross-border deals surged; PE remained disciplined amid uncertainty.
Redefining operational due diligence in India’s evolving deal landscape
Operational due diligence in India is evolving from risk mitigation to execution certainty, shaping value creation in private equity and M and A deals.
Nine years of IBC: Transforming India’s insolvency landscape
IBC’s nine-year journey shows stronger credit discipline, faster revival, and improved NPAs, while delays and the 2025 Amendment Bill aim to modernize insolvency reforms.
Why India’s deal market in Q3 2025 signals long-term M&A resilience
India’s M&A market rebounds in Q3 FY25 with deals worth US$28B, up 19% QoQ. Automotive, lifesciences, and tech sectors lead as mid-sized transactions gain momentum.
EPR compliance: The new ESG test for Indian companies
EPR compliance is reshaping ESG in India non-compliance risks fines and lower valuations, while sustainability leaders gain a competitive edge.
Navigating the M&A landscape of India: Insights of H1 2025
India's H1 2025 Merger & Acquisitions activity reaches US$50B, led by major transactions, strong power sector growth & steady domestic and PE engagement.
Connecting the dots: M&A deals in the technology services in 2024
Discover key trends in 2024 M&A for technology services, with 850+ deals, $30B+ value, PE-backed roll-ups, and insights on cloud, AI, and digital transformation. Learn more.
How India Inc. can navigate the road to financial resilience
Explore key findings from the 2024 Cost of Capital Survey, revealing insights into India Inc.'s financial resilience and strategic growth.
Driving Competitive Differentiation: M&A Outlook for 2023 in Tech Services
Discover how Tech Services M&A activity has slowed in 2023 but long-term sustainable tailwinds and underlying digital transformation theme remains structurally strong.
Frequently Asked Questions (FAQs)
Direct to your inbox
Stay up to date with our Editor's picks newsletter.