

EY refers to the global organization, and may refer to one or more, of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients.
Recent Searches
Press release
08 Sept 2026
|
Mumbai, India
India's healthcare providers sustain double-digit growth in Q1FY27 amid affordability push: EY Report
Mumbai, India, 08 September 2026: Leading Indian hospital operators continued to report double-digit revenue growth, supported by higher occupancy, an improving specialty mix and increased contribution from advanced procedures, as per the latest EY healthcare sector update. At the same time, the sector is preparing for a potentially evolving regulatory landscape following the release of the Parliamentary Standing Committee's report on affordability and accessibility of healthcare.
The quarter saw a y-o-y revenue growth upwards of 15% across several large hospital networks, supported by patient volume growth, improved pricing and greater adoption of advanced clinical services. Operating performance remained resilient, although margins in some cases moderated due to the ramp-up of newly commissioned assets, acquisitions and investments in future capacity.
A key theme emerging across the sector is the unprecedented scale of capacity creation. Multiple healthcare providers announced ambitious expansion plans, with several large hospital platforms targeting thousands of additional beds over the next few years.
The diagnostics sector similarly delivered a strong quarter, aided by healthy growth in patient and test volumes, preventive healthcare adoption and continued network expansion. Revenue growth across major diagnostics providers remained upwards of 10% year-on-year.
Specialty healthcare segments also maintained momentum. Oncology, paediatric and ophthalmology-focused providers reported strong growth in volumes and revenues, supported by network expansion and increasing patient demand. Medical device manufacturers recorded healthy revenue growth, particularly in export markets, although some companies highlighted pressure from geopolitical disruptions, elevated input costs and pricing competition in select regions.
Commenting on the analysis, Kaivaan Movdawalla, National Healthcare Leader, EY Parthenon India said, "The strong start to FY27 underscores the resilience of India’s healthcare sector. Robust patient volumes, rising demand for high-acuity treatments and aggressive capacity creation across hospitals and diagnostics continue to support growth. At the same time, the Parliamentary Committee’s recommendations highlight the increasing policy focus on affordability, transparency and access.”
Adding to it, Amit Gupta, Partner – Healthcare and Life Sciences Investment Banking, EY India said, “As organizations invest across the care continuum, investor attention is likely to remain focused on occupancy ramp-up, margin realization and the pace at which newly commissioned assets contribute to earnings. The sector's ability to maintain growth while absorbing significant expansion costs will be a key differentiator going forward."
The publication of the Department-related Parliamentary Standing Committee on Health and Family Welfare's report proposes a wide-ranging set of recommendations aimed at reducing out-of-pocket expenditure, improving financial protection and strengthening healthcare accessibility. Key proposals include greater standardization of healthcare pricing, expanded insurance coverage for outpatient treatments and diagnostics, increased transparency in billing practices, regulation of treatment and diagnostic pricing, and enhanced quality assurance requirements across healthcare institutions.
As the sector enters the remainder of FY27, growth is increasingly being shaped by scale, clinical complexity, technology adoption and network expansion. While healthcare organizations continue investing in new capacity and advanced care delivery, the evolving policy dialogue around affordability and accessibility is set to remain a key area of focus for industry stakeholders.
About the report
The findings are based on EY's Q1FY27 Healthcare Sector Update, which analyzes the quarterly performance of listed healthcare providers, diagnostics chains, specialty hospitals and medical device companies, alongside key policy developments affecting the sector.
About EY
EY is building a better working world by creating new value for clients, people, society, and the planet, while building trust in capital markets. Enabled by data, AI and advanced technology, EY teams help clients shape the future with confidence and develop answers for the most pressing issues of today and tomorrow.
EY teams work across a full spectrum of services in assurance, consulting, tax, strategy, and transactions. Fueled by sector insights, a globally connected, multi-disciplinary network and diverse ecosystem partners, EY teams can provide services in more than 150 countries and territories.
All in to shape the future with confidence.
EY refers to the global organization and may refer to one or more of the member firms of Ernst & Young Global Limited, each of which is a separate legal entity. Ernst & Young Global Limited, a UK company limited by guarantee, does not provide services to clients. Information about how EY collects and uses personal data and a description of the rights individuals have under data protection legislation are available via ey.com/privacy. EY member firms do not practice law where prohibited by local laws. For more information about our organization, please visit ey.com. This news release has been issued by EYGM Limited, a member of the global EY organization that also does not provide any services to clients.
Related content
Mumbai, 20 August 2026 – Domestic funds emerged as the dominant force in India's private credit market in H1 2026, accounting for 74% of total deal value and nearly 79% of deal volume, according to the EY Private Credit Report H1 2026. The market remained resilient during the period, with investments reaching US$3.5 billion across more than 100 transactions above US$10 million, broadly in line with US$3.4 billion recorded in H2 2025.
New Delhi, 17 August 2026: EY India and Shri Ram College of Commerce (SRCC) today launched AI VIBE (Varsity for Innovation, Business and Economics), a first-of-its-kind industry-academia initiative designed to prepare students for careers in an AI-enabled economy.
PE/VC investments in India reach US$20.5 billion across 604 Deals in 1H2026: EY-IVCA Report
Mumbai, 31st July 2026. PE/VC investments in India reach US$20.5 billion across 604 Deals in 1H2026 according to the EY-IVCA Report
Mumbai, 22 July 2026. India Healthcare Sector Records Strong FY26 Growth; Expansion and Capacity Build-Out Drive Momentum according to the EY-Parthenon Report.
New Delhi, 9 July 2026, EY India launches AI-powered Cyber Performance Management platform to help enterprises quantify cyber risk in real time.
New Delhi, 18 June 2026.GenAI could deliver up to 50% higher sales velocity and faster launches for India’s real estate sector according to the EY-Parthenon-CREDAI report.
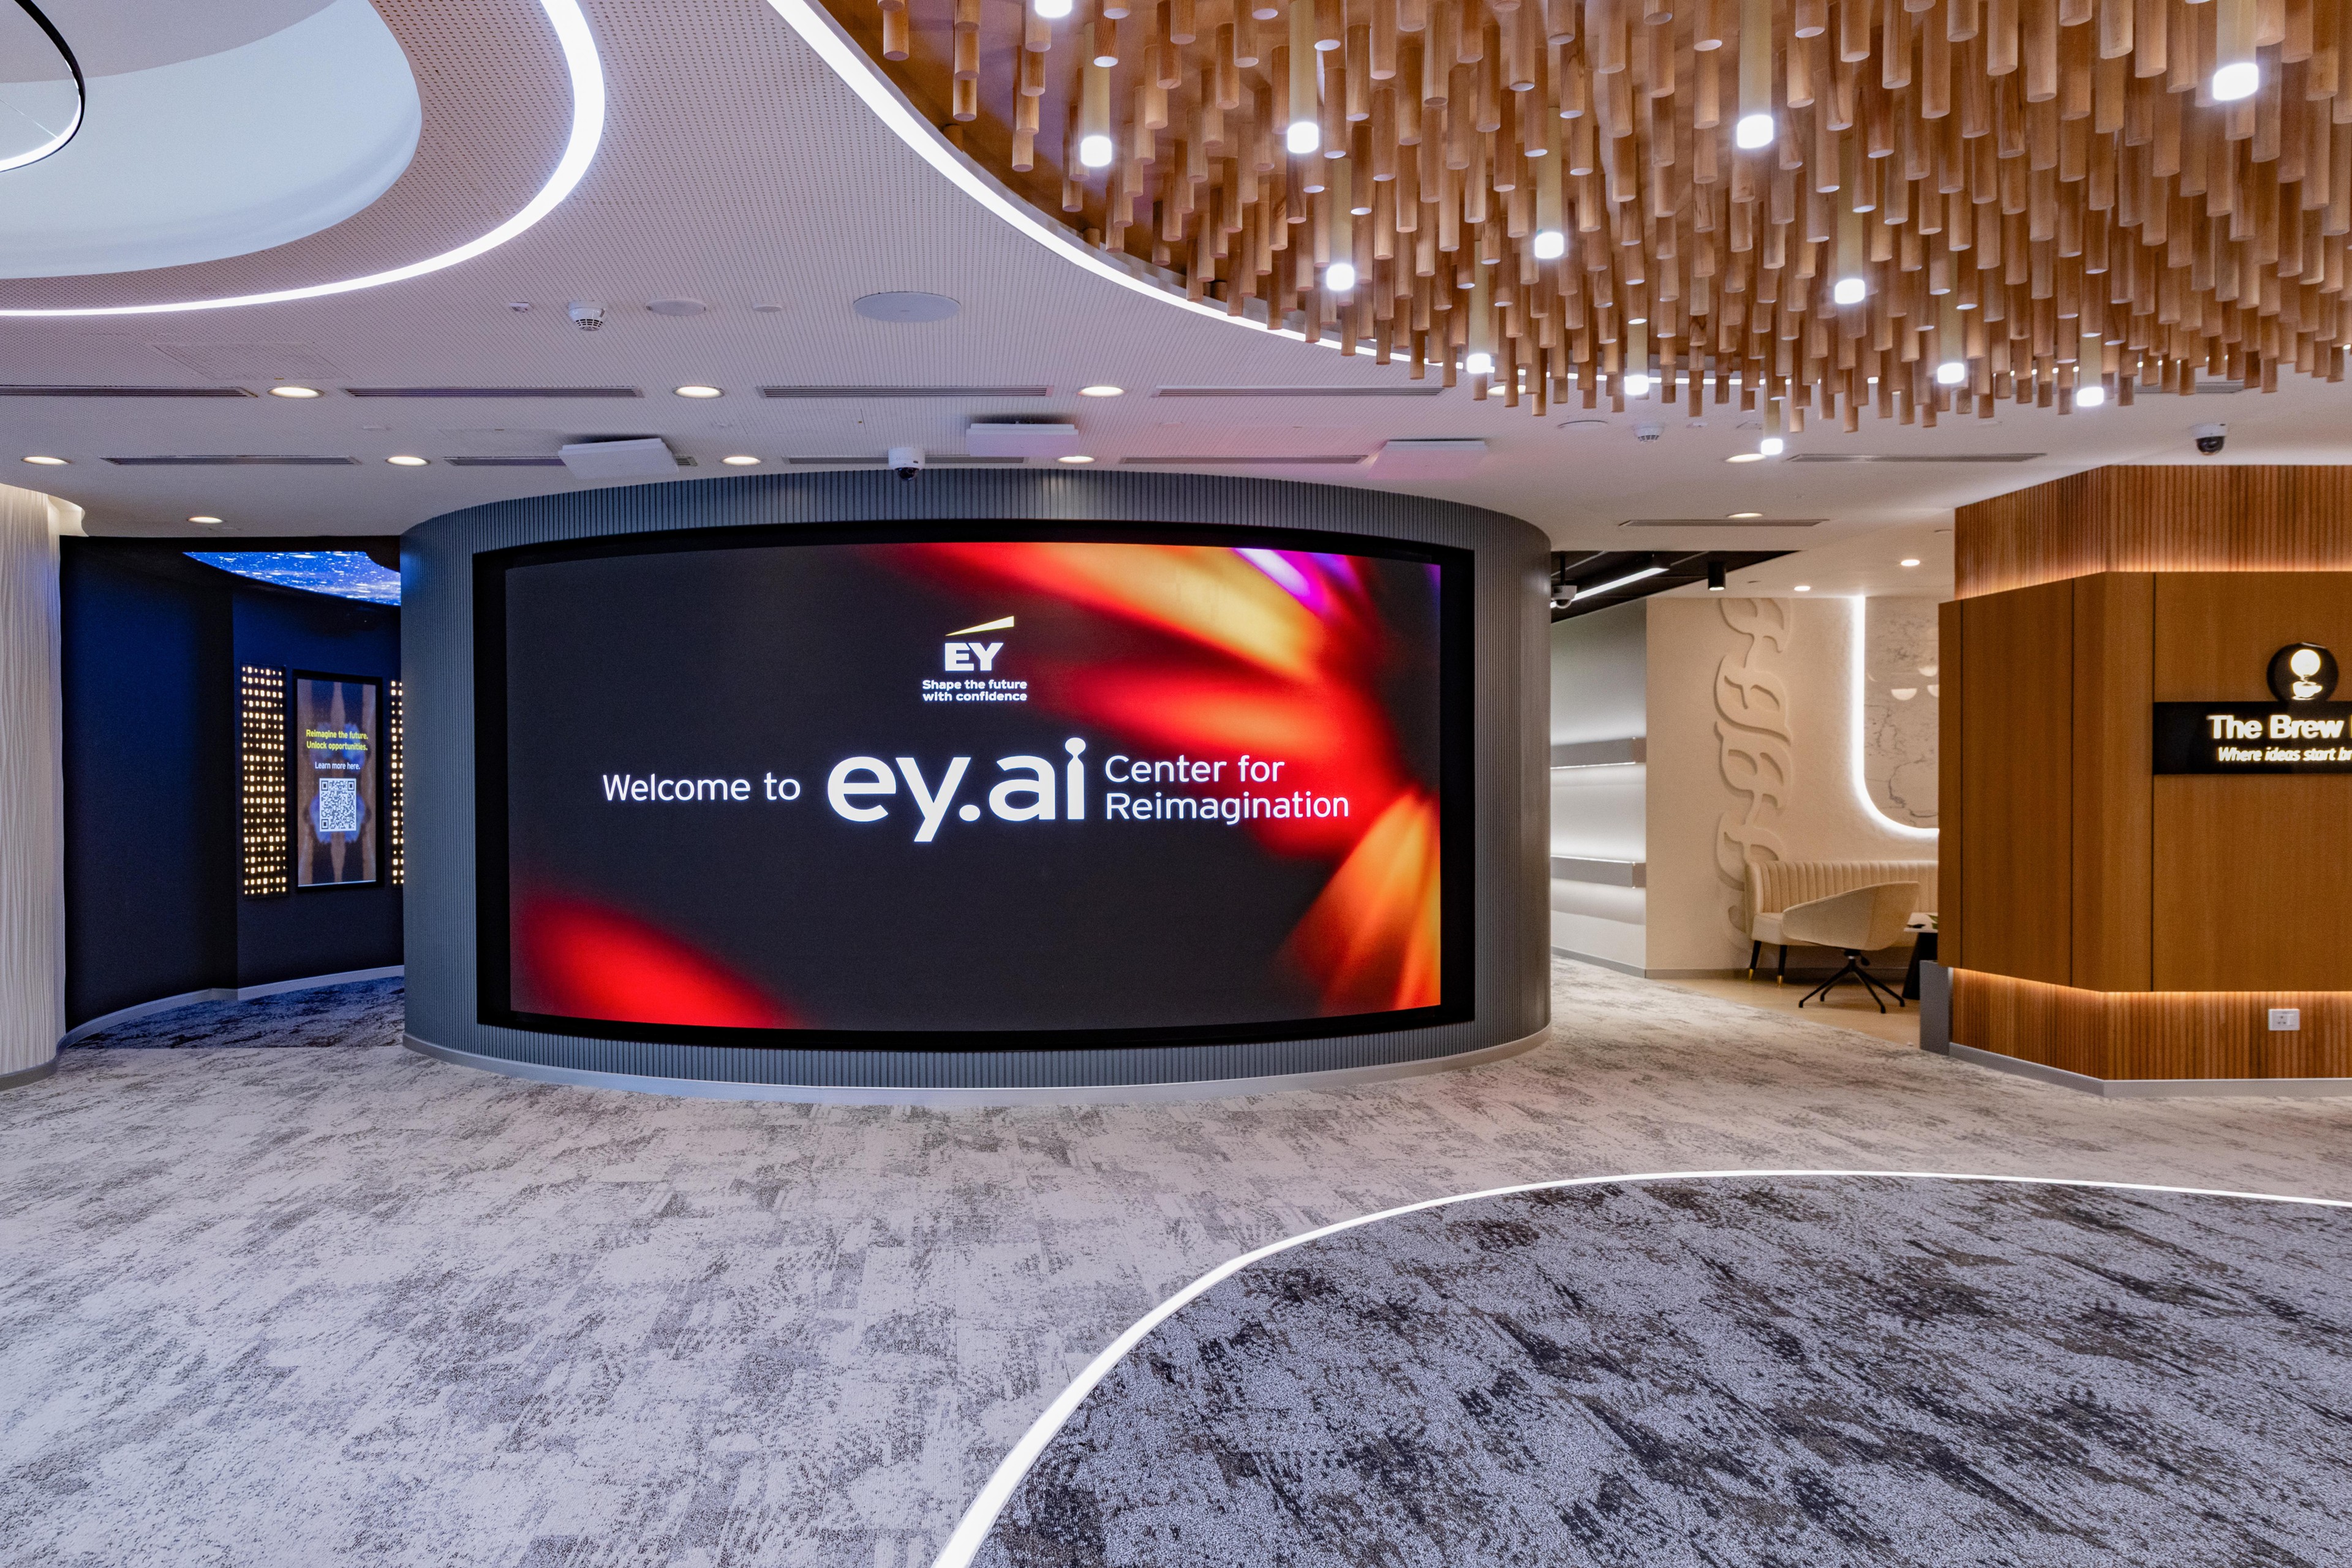
EY GDS launches ey.ai Center for Reimagination in Bengaluru
Bengaluru, India; June 11, 2026. EY GDS launches Bengaluru-based ey.ai Center for Reimagination, enabling AI-powered innovation, design thinking and enterprise growth.
Guwahati, June 10, 2026 – Assam emerges as India’s next concert economy hub; BookMyShow and EY-Parthenon project a ₹700 crore economic opportunity over the next five years.
New Delhi | 12 May 2026.EY India named among LinkedIn Top Companies 2026 as Indian firms shift focus to long-term careers and skills
Mumbai, 30 April 2026.Indian PE/VC investment activity moderates to US$13.1 billion across 360 Deals in 1Q2026 according to the EY-IVCA Report.
Mumbai, 27 March 2026: According to the EY-IVCA monthly PE/VC roundup, private equity and venture capital investments in India decreased by 3% in February 2026 compared to January 2026 in value terms.
India’s media and entertainment (M&E) sector continued its expansion in 2025, driven primarily by digital media, advertising & live experiences.
Sardar Patel Institute of Technology, Mumbai, wins EY Techathon 6.0
Sardar Patel Institute of Technology wins EY Techathon 6.0; Techno Engineering College is runner‑up and IIT Roorkee earns People’s Choice Award for AI innovation.
India’s ₹13,000 crore live events market is driving a major shift to experiential marketing, with rising brand recall, purchase intent and experience-led consumer behavior
India’s PE/VC industry staying on the front foot despite global headwinds: EY–IVCA Trendbook 2026
Read how Indian PE/VC investments continued their upward trajectory, reaching US$60.7 billion across 1,475 deals—an 8% year on year increase.
Dil‑Luminati India Tour 2024 generated over INR943 crore in economic impact: EY report estimates
Mumbai, 5 March 2026.Dil Luminati India Tour 2024 generated over INR943 crore in economic impact according to the EY report estimates.
New Delhi, 23 February 2026India Inc. projects 9.1% salary increase in 2026 as compensation becomes sharper, more skills-led according to the EY Future of Pay 2026 report.
Mumbai, 27 January 2026. India’s Over-The-Counter drugs market set to hit ₹98,000 Crore by 2030, growing at 13% CAGR according to the EY Parthenon report.
Mumbai, 15 January 2026. India’s healthcare sector records cumulative deal value of over INR 10,000 crore in Q2 FY26 according to the EY Parthenon Report.
PE/VC Investments in India reach 88% of 2024 levels as 2025 nears close: EY-IVCA Report
Mumbai, 23 December 2025.PE/VC Investments in India reach 88% of 2024 levels as 2025 nears close according to the EY-IVCA Report.
India leads globally on AI Advantage at work; 86% employees cite positive impact of GenAI on productivity according to the EY 2025 Work Reimagined Survey.
HSBC and EY India unveil a Comprehensive Compendium on GIFT City, signalling next phase of global integration and market maturity.
NEW DELHI, December 1, 2025 .Odisha needs 26,237MW of total contracted capacity to meet rising power demand by 2034 according to the EYASSOCHAM report.
PE/VC Investments in India reach US$5.3 billion across 102 deals in October 2025 : EY-IVCA Report
Mumbai, 28 November 2025.PE/VC Investments in India reach US$5.3 billion across 102 deals in October 2025 according to the EY-IVCA Report.
58% GCCs in India investing in Agentic AI; two-third creating dedicated innovation teams to globalize ideas according to the EY GCC Pulse Survey 2025.
Indias AI shift from pilots to performance; 47% of enterprises have multiple AI use cases live in production according to the EY-CII Report.
PE/VC Investments in India reach US$11.7 billion across 369 deals in 3Q2025 : EY-IVCA Report
Mumbai, 18 October 2025. PE/VC Investments in India reach US$11.7 billion across 369 deals in 3Q2025 according to the EY-IVCA Report
EY and Microsoft launch AI Skills Passport to equip India’s youth with AI driven future
New Delhi, 9 October 2025 – In a significant effort to bridge the AI skills gap in India, EY and Microsoft have launched the AI Skills Passport - a free, online program that provides equitable access to high-quality AI education for youth aged 16 and older.
New Delhi, 09 October 2025.Transparency drives patient choice; 9 in 10 Indians willing to pay more for certified healthcare according to FICCI- EY-Parthenon report
PE/VC Investments in India reach US$2.8 billion across 115 deals in August 2025: EY-IVCA Report
Mumbai, 29 September 2025: According to the EY-IVCA monthly PE/VC roundup, private equity and venture capital investments in India decreased by 31% in August 2025 compared to July 2025 in value terms.
India’s FY26 growth outlook raised to 6.7% on back of monetary easing and GST 2.0 reforms: EY India
- New Delhi, 29 September 2025. India’s FY26 growth outlook raised to 6.7% on back of monetary easing and GST 2.0 reforms according to the EY India
New Delhi, 26 September 2025. EY India launches Automated Regulatory Tool built on Snowflake to transform financial reporting compliance; aims to automate 80% of reporting.
India Needs 40x Surge in Non-Fossil Energy to meet Viksit Bharat 2047 Vision: EY–CII report
EY–CII report reveals India must triple energy supply and scale non-fossil sources 40× to achieve Viksit Bharat 2047, while managing affordability and security.
EY India Techathon 6.0 engages with young innovators to shape the AI leaders of tomorrow
New Delhi, 18 September 2025. EY India Techathon 6.0 engages with young innovators to shape the AI leaders of tomorrow.
Mumbai, 17 September 2025 – Indian treasury teams are at a pivotal point in their evolution, ranking automation as their top investment priority as per EY India Corporate Treasury Survey 2025.
Coking coal imports to rise, steel for 300 MT, 2030
Read how India’s steel sector needs will push coking coal imports up as steel capacity targets 300 MT by 2030 amid sustainability and supply chain shifts.
How Indian hospitals plan to raise IT innovation spends by 20-25% in 2-3 years with AI, automation, data tools and patient-centric care as top priorities.
Bengaluru, 1 September 2025.India emerges as lifesciences GCC hub; nearly half of top 50 global firms establish presence, with significant entries in past 5 years accorsing to the EY analysis.
Read how India could become the world’s 2nd largest economy by 2038 with a projected US$34.2T GDP, backed by strong demographics, reforms and PPP growth.
PE/VC Investments in India reach US$4 billion across 115 deals in July 2025: EY-IVCA Report
Read how India’s PE/VC investments hit US$4B in July 2025 over 115 deals boosted by fintech, healthcare exits, strong deal flow and investor confidence.
Read how India’s outbound investments surged ~67% to US$41.6B in FY25 - driven by ESG, GIFT City expansion, global tax reforms and sector diversification
How India’s private credit market surged 53% H1 2025 to US$9B, led by US$3.1 billion deal driven by infrastructure, real estate, healthcare & global funds
EY India appoints Gaurav Bhalotia as Chief Technology Officer
Read how EY India strengthens innovation & AI-led digital solutions with Gaurav Bhalotia, former Udaan, with 20+ years in large-scale tech & product leadership.
India’s M&A activity holds ground with US$50.5B in deal value in H1 2025: EY M&A Report
Read how India’s M&A held firm at over US$50B in H1 2025 despite a 12% dip in transaction volume, driven by major power and high-value renewables deals.
CXOs need to do more to build customer trust in their AI deployments: EY India
How CXOs can bridge trust gaps in AI, only 30% have scaled AI, 37% lack governance, while consumers worry about misinformation, job loss & loss of control.
PE/VC Investments in India reach US$26.4 billion across 593 deals in 1H2025: EY-IVCA Report
Mumbai, 29 July 2025, PE/VC Investments in India reach US$26.4 billion across 593 deals in 1H2025 according to the EY-IVCA Report.
EY Parthenon report reveals India's green steel demand to surge to 179 million tons by 2050
New Delhi, July 28, 2025. NEW DELHI, July 28, 2025. EY Parthenon report reveals India's green steel demand to surge to 179 million tons by 2050
21 July 2025, New Delhi / Mumbai. ‘Mobility’ key differentiator in global talent strategy, 81% Indian employees find it to be career-transforming according to the EY report