Team members collaborating in a bright, glass-enclosed meeting room

Merger Monthly series

US M&A activity insights: August 2026


Strategic megadeals powered US M&A gains from June through August 2026.


In brief
  • M&A activity and deal value increases show broad-based growth in three months ended August 31.
  • Ready access to private credit helps buyers expand technology platforms and capabilities.
  • Technology, life sciences, and aerospace and defense/mobility lead deal activity.

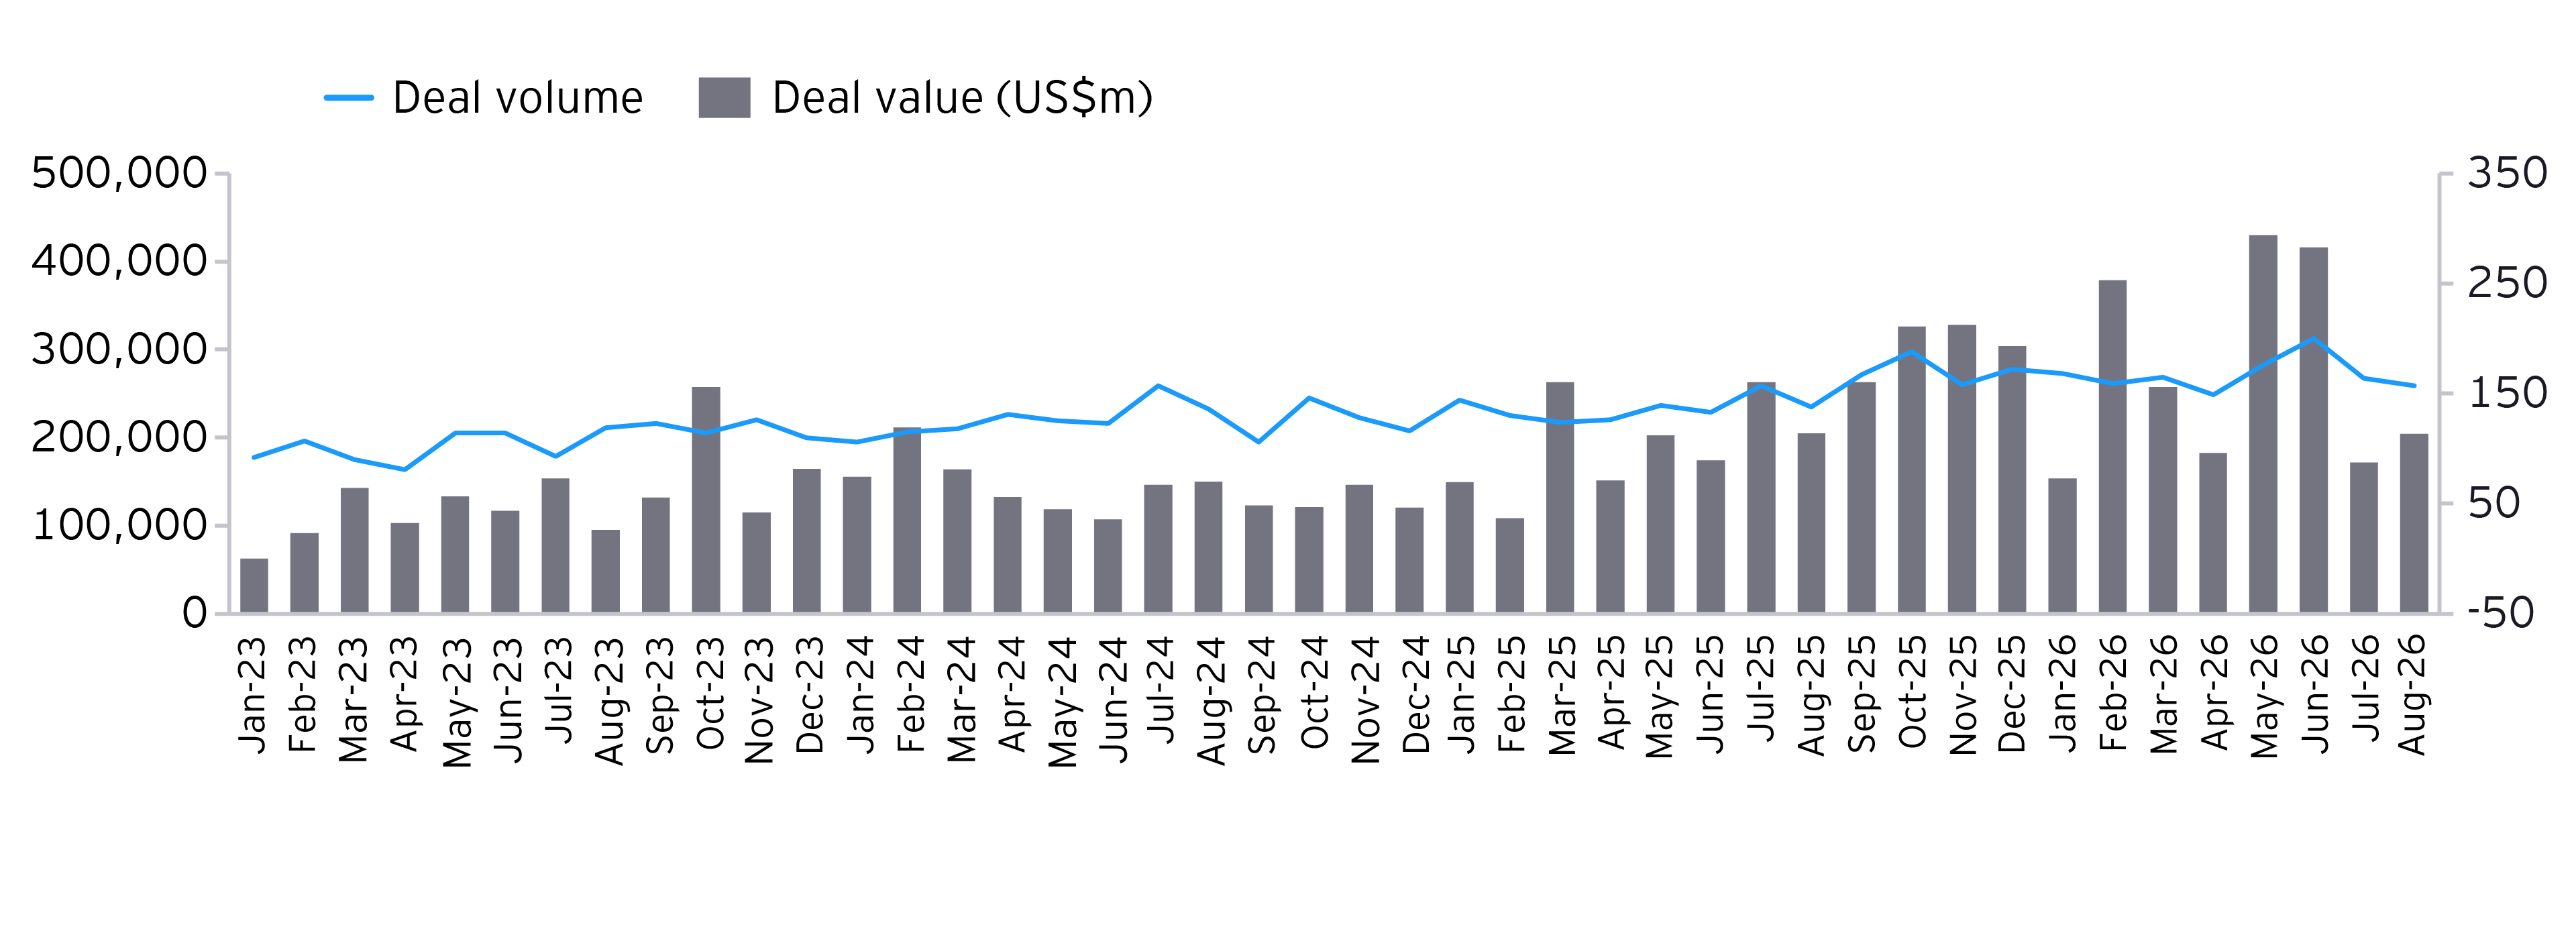
US mergers and acquisitions (M&A) activity strengthened from June through August 2026 as strategic buyers and financial sponsors accelerated capital deployment. Transactions valued at US$100 million or more increased 22% in value and 23% in volume from the prior year, indicating broad-based growth rather than reliance on a few megadeals.1 Acquirers capitalized on robust private credit availability to pursue scale and fund consolidations. The market also continues to reflect a shift toward strategy-led dealmaking, with organizations using M&A to accelerate transformation, acquire critical capabilities and strengthen long-term competitive positioning.

Source: EY insights analysis and Dealogic.

The sustained increase in deal activity reflects growing confidence in the underlying economic environment. According to EY-Parthenon Chief Economist Gregory Daco, the US economy is expected to expand at a 2% pace, supported by an 8.5% rise in business investment and continued strength in AI-related capital spending. Corporate profits increased by ~US$401 billion in Q2’26, lifting profit margins and reinforcing corporate balance-sheet strength. However, modest real income growth, slowing consumer momentum and softer labor conditions point to an uneven outlook. As a result, buyers remain highly selective, concentrating capital on opportunities with a clear strategic rationale, differentiated capabilities and identifiable value-creation pathways.

Monthly M&A trend (2023 onward)

Deal value (US$100m+), deal volume (US$100m+)

Monthly M&A trends chart - August

Source: EY insights analysis and Dealogic.


Acquiring differentiated platforms, data and technology capabilities

Recent transactions show continued buyer interest in technology platforms, proprietary data and specialized capabilities that would be difficult or time consuming to build internally. These assets support faster product development, broader distribution, integrated workflows and stronger customer propositions across research, commercial and digital channels. The strategic intent is to accelerate technology enablement, deepen customer relationships and create cross-selling opportunities, thereby highlighting continued focus on acquisitions that drive sustainable growth.

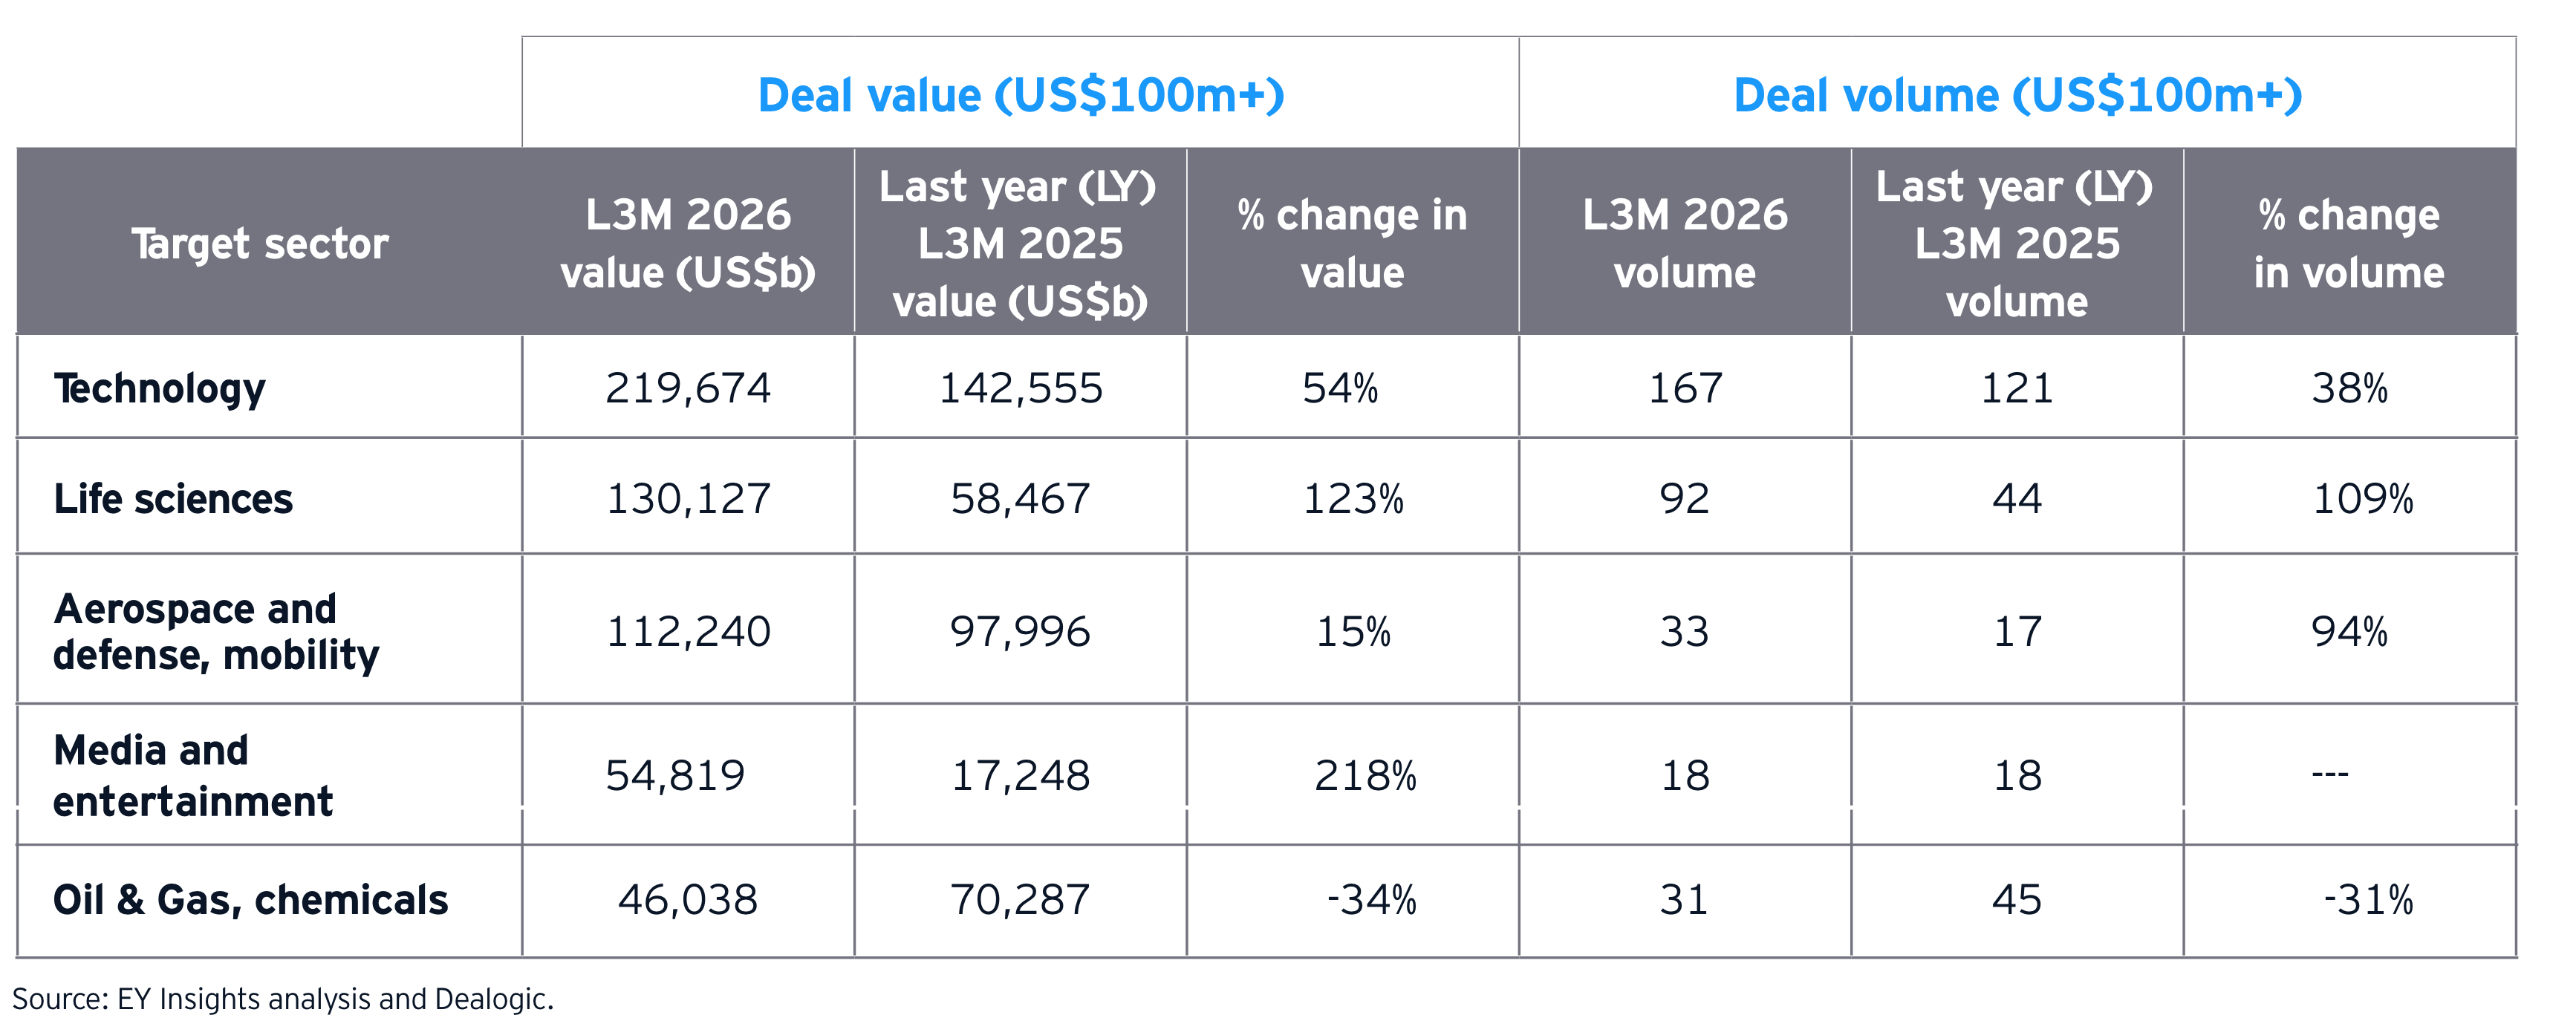
US sector breakdown for top deals (US$100m+)

Sectors that fueled deal activity in Jun-Aug 2026 (last three months (L3M)

US sector breakdown for top deals - jun-aug 2026

Sector highlights

M&A activity from June through August recorded significant growth in both deal value and volume compared with a year earlier across most of these sectors:

Technology

Dealmaking strengthened, with deal value increasing 54% and volume rising 38%, indicating broad-based activity. Dealmaking centered on AI and data capabilities, edge computing, connected platforms and power-secured digital infrastructure.

"We are seeing deal activity not just from the hyperscalers, but in the picks and shovels that support AI expansion, including proprietary data, automation capabilities and infrastructure, as companies look to accelerate enterprise-wide AI deployment and strengthen their market position," Malinda Gentry, partner at EY-Parthenon and Americas Technology, Media and Telecommunications Industry Leader, said.

Life sciences


M&A surged, with deal value increasing 123% and volume rising 109%, driven by growing demand for integrated diagnostics, life sciences tools, specialized care infrastructure and scalable manufacturing capabilities. Buyers prioritized pipeline expansion and therapeutic diversification, targeting differentiated late-stage assets and novel treatment platforms.


Aerospace and defense, mobility


M&A accelerated, with deal value rising 15% and volume increasing 94%, indicating that growth was driven primarily by a larger number of smaller transactions. Activity reflected geographic expansion and investment in manufacturing capacity aligned with defense modernization and space mobility demand. Buyers pursued greater scale, specialized engineering capabilities and supply chain consolidation.


Media and entertainment


Deal value surged 218% while volume remained flat, indicating that growth was concentrated in fewer, larger transactions. Activity focused on premium sports franchises, live entertainment venues, gaming and hospitality platforms, and scaled media assets. Buyers targeted businesses with durable brand value, recurring revenues and monetizable audiences, seeking to expand consumer reach and deepen engagement across physical and digital channels.


Oil and gas, chemicals 


M&A moderated, with deal value declining 34% and volume falling 31%, reflecting selective capital deployment. Activity pointed to consolidation and vertical integration, particularly across midstream infrastructure, natural gas processing and specialty chemicals. Buyers targeted scaled assets in core basins to expand capacity and capture operating synergies.
Looking ahead

For the remainder of 2026, M&A activity is likely to remain supported by resilient corporate confidence and continued strategic urgency. However, the recovery will remain uneven, with well-capitalized buyers prioritizing larger, high-conviction opportunities while valuation gaps, geopolitical uncertainty and tighter underwriting continue to influence deal timing, structuring and execution, particularly outside the most attractive segments of the market.

Companies are expected to continue using M&A as a strategic lever for transformation, helping accelerate access to technology, capabilities and infrastructure while repositioning portfolios toward long-term growth priorities. AI-related demand should continue to influence activity beyond technology, particularly across data centers, power and digital infrastructure. At the same time, divestitures and carve-outs will remain important as companies simplify portfolios and redirect capital toward core growth areas.

Private equity activity is likely to remain selective as sponsors balance significant deployment pressure and aging portfolios against continued valuation discipline and constrained exit markets. Continuation vehicles and other alternative liquidity solutions are likely to remain important as sponsors seek liquidity while maintaining valuation discipline.

Overall, successful dealmaking will depend on strategic clarity, disciplined pricing, rigorous diligence and early integration planning. As competition intensifies for high-quality assets, the most successful acquirers will be those that translate transaction ambition into measurable and sustained business value.


Summary

M&A activity showed strength in the three months ended August 31, boosted by strategic acquisitions to accelerate technology enablement, deepen customer relationships and create cross-selling opportunities. Technology, life sciences, and aerospace and defense were among the most active sectors, while acquirers had robust access to private credit to support deals.

Explore recent editions


US M&A Insights
July 2026


US M&A Insights
June 2026


US M&A Insights
May 2026


About this article

Authors


Contact our M&A advisory team
Get in touch to learn how EY can help with your M&A strategy. 

Related articles

Private Equity Pulse: key takeaways from Q2 2026

The PE Pulse is a quarterly report that provides data and insights on private equity market activity and trends. Read the latest report.

EY-Parthenon forecasts resilient 8% growth in US dealmaking in 2026 despite geopolitical and economic headwinds

The EY-Parthenon Deal Barometer projects 8% growth in US M&A 2026 deal volumes. Get the latest M&A outlook on US deals, mergers and acquisitions, and dealmaking trends.

Can disciplined ambition unlock growth in a volatile global economy?

Explore CEO 2026 priorities: disciplined growth that ties AI to ROI, embeds geopolitics into strategy and uses M&A to compete amid volatility.

Macro Bites: PE deals increase as valuation gaps shrink, dry powder available

Private equity leaders should invest in AI, prepare for exits, and engage stakeholders to seize new market opportunities. Watch more on Macro Bites.